Inheriting a property can be one of the most significant financial events in a person's life. But what happens when you don't inherit the entire property — only a share of it? Understanding mortgage requirements for inherited fractional ownership properties is something many heirs find confusing, and for good reason. The rules surrounding shared ownership, lender eligibility standards, and title complications can make financing feel overwhelming. Whether you've recently inherited a partial interest in a family home or a piece of investment real estate, this guide will walk you through what you need to know to move forward with confidence.
What Is Inherited Fractional Ownership?
Fractional ownership occurs when multiple parties hold a legal interest in a single property. When someone passes away and leaves real estate to more than one heir, each heir typically receives a fractional share of that property. This type of shared ownership is sometimes referred to as tenancy in common, where each co-owner holds a distinct, divisible percentage of the property rather than an equal undivided share.
For example, if a parent leaves a home equally to three adult children, each child may own roughly one-third of the property. That fractional interest is legally real and recordable — but it creates complications when any one heir wants to borrow against their share or buy out the others.
It's important to understand that fractional ownership is different from joint tenancy, where surviving co-owners automatically absorb the deceased's share. With inherited fractional interests, each heir's portion is typically established through a will, trust, or state intestacy laws, and the ownership structure can vary significantly from one estate to the next.
Why Lenders View Fractional Interests Differently
From a lender's perspective, a fractional ownership interest presents a unique set of risks that aren't present in a standard single-ownership mortgage transaction. When a borrower owns 100% of a property, a lender can place a first lien on the entire asset and foreclose on the whole property if the loan defaults. With a fractional interest, however, that security becomes more complicated.
Most conventional mortgage lenders — including those following Fannie Mae and Freddie Mac guidelines — typically require that the borrower hold clear title to the entire property before approving a traditional mortgage. This means that if you only own a share of an inherited property, you may not qualify for a standard conforming loan against your fractional interest alone.
Lenders may also be concerned about:
- Title encumbrances: Other co-owners' interests can cloud the title, making it difficult for lenders to secure a clean first lien position.
- Co-owner disputes: If other heirs disagree about how the property is managed or whether to sell, lenders may see this as a risk to their collateral.
- Forced partition actions: Any co-owner can potentially file a partition lawsuit, which could result in a court-ordered sale of the property — complicating a lender's ability to recover funds.
- Appraisal challenges: Valuing a fractional interest is more complex than valuing a whole property, and lenders rely heavily on clear appraisals for underwriting purposes.
These concerns don't make borrowing impossible, but they do mean that heirs with fractional interests often need to explore non-traditional lending paths or take steps to consolidate ownership before applying for financing.
Steps Heirs Often Take Before Applying for a Mortgage
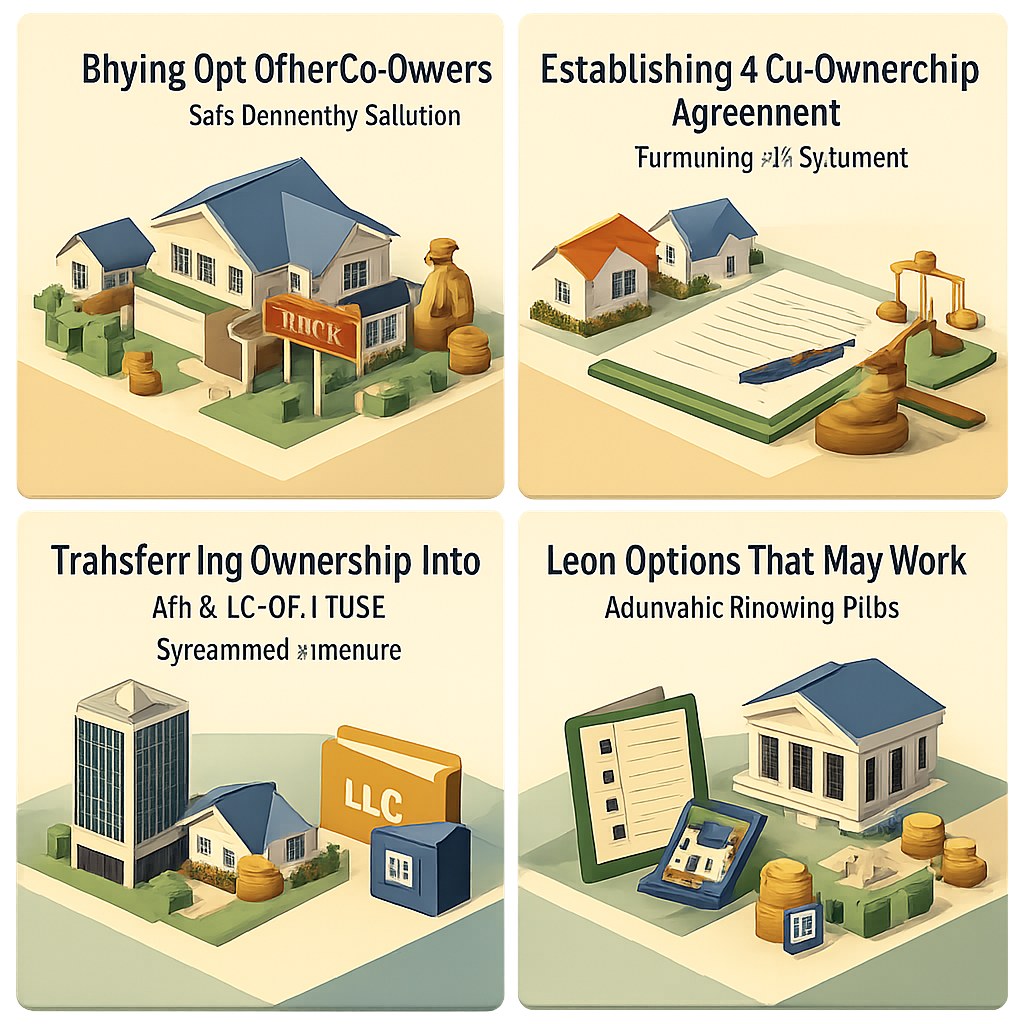
Because of the complications described above, many heirs find it advantageous to resolve the ownership structure before approaching a mortgage lender. Here are some common strategies that may simplify the path to financing:
Buying Out Other Co-Owners
One of the most straightforward solutions is for one heir to purchase the other heirs' shares, thereby becoming the sole owner of the property. This buyout might be funded through personal savings, a short-term personal loan, or sometimes through an estate loan or probate loan designed specifically for this purpose. Once clear title is established, the new sole owner can typically apply for a conventional mortgage with far fewer obstacles.
Establishing a Co-Ownership Agreement
If a buyout isn't financially feasible, co-owners might consider drafting a formal co-ownership or tenancy in common agreement. This legal document outlines each party's rights, responsibilities, and financial obligations. Some lenders — particularly portfolio lenders and private lenders — may be more willing to work with borrowers who have a structured agreement in place, as it reduces the perceived risk of co-owner disputes.
Transferring Ownership into an LLC or Trust
In some cases, heirs choose to transfer the inherited property into a limited liability company (LLC) or a family trust. This approach can streamline the ownership structure, but it's worth noting that many conventional mortgage programs don't lend to LLCs for residential properties. This path may be more relevant for investment properties financed through commercial or portfolio loan products.
Loan Options That May Work for Fractional Ownership Situations
While conventional mortgage guidelines can be restrictive for fractional ownership scenarios, several alternative financing options for fractional ownership may be available to heirs who need to act before full ownership is consolidated.
Portfolio Loans
Portfolio lenders are banks or credit unions that keep their loans in-house rather than selling them to the secondary market. Because they're not bound by Fannie Mae or Freddie Mac guidelines, portfolio lenders may have more flexibility in underwriting fractional ownership situations. They can set their own credit and collateral standards, which might allow them to consider a borrower's partial interest in an inherited property.
Hard Money or Private Loans
Hard money lenders focus primarily on the value of the real estate rather than the borrower's credit profile. These short-term loans typically carry higher interest rates and fees, but they can sometimes be arranged more quickly and with less rigid title requirements. For heirs who need temporary financing to buy out siblings or cover estate costs, a hard money loan might serve as a bridge solution — though it should be used carefully given the cost involved.
Home Equity Products on Inherited Whole Properties
If you've inherited a property outright and are now the sole owner, home equity loans and HELOCs (home equity lines of credit) may become available tools. These products allow you to borrow against the equity in the home without refinancing the full mortgage. They can be useful for consolidating a fractional interest or making improvements to increase the property's value.
Estate and Probate Loans
Specialized lenders sometimes offer estate loans or probate loans designed specifically for heirs who need funds while an estate is being settled. These loans are typically short-term and are secured by the estate's assets, including the inherited property. They can be a practical tool for heirs who want to stabilize their financial position before pursuing a long-term mortgage solution.
Credit and Income Qualification Factors That Still Apply
Even when the ownership and title issues are resolved, heirs must still meet standard mortgage qualification requirements. Understanding inherited property mortgage rules fractional ownership doesn't exempt borrowers from the normal underwriting process. Lenders will typically evaluate:
- Credit score: Most conventional loans require a minimum credit score, often in the mid-600s or higher. FHA loans may allow lower scores, though specific thresholds vary by lender.
- Debt-to-income ratio (DTI): Lenders assess how much of your monthly gross income goes toward existing debt payments. A lower DTI generally improves your chances of approval and may help you qualify for better rates.
- Income documentation: Whether you're employed, self-employed, or relying on rental income from the inherited property, lenders will want to verify your ability to repay the loan.
- Down payment or equity: If you're refinancing an inherited property you now own outright, the built-in equity can work in your favor. If you're purchasing other co-owners' shares, the down payment requirements will depend on the loan type and lender.
It's also worth noting that some lenders may require a waiting period after the estate is fully settled before they'll consider the property eligible for standard mortgage financing. Checking with individual lenders early in the process can help you understand what timeline to expect.
Working With Professionals to Navigate Inherited Property Financing
Given the legal and financial complexity involved in understanding mortgage requirements for inherited fractional ownership properties, working with the right team of professionals can make a meaningful difference in your outcome.
Real Estate Attorney
An attorney who specializes in estate and real estate law can help you navigate financing options, draft co-ownership agreements, and advise on whether a partition action is a risk you need to address. Legal guidance early in the process can prevent costly surprises later.
Estate or Probate Specialist
If the estate hasn't been fully settled, a probate specialist or estate administrator can help move the process along. Getting the estate closed and title transferred correctly is often a prerequisite for mortgage approval.
Mortgage Broker or Loan Officer
A knowledgeable mortgage broker can help you shop multiple lenders — including portfolio and specialty lenders — who may be open to working with fractional or recently inherited properties. They can also help you understand which loan programs you might realistically qualify for given your specific situation.
Tax Advisor
Inheriting property can have tax implications, including potential capital gains exposure depending on your state and holding period. A tax professional can help you understand the cost basis of the inherited property and what to expect if you sell or refinance.
●Conclusion
Navigating the mortgage process as an heir with a fractional property interest is genuinely challenging — but it's not impossible. The key is to understand the landscape early, address title and co-ownership issues proactively, and work with lenders and professionals who have experience in these types of transactions. Understanding mortgage requirements for inherited fractional ownership properties gives you a meaningful head start in making smart, informed decisions about your inherited real estate. Whether your goal is to keep the property, buy out other heirs, or eventually refinance into a long-term mortgage, taking deliberate steps now can open more doors down the road. LoanWise is here to help you explore your options and find the financing path that fits your situation best.