Purchasing a high-value home often means stepping into jumbo loan territory — and that comes with a more rigorous approval process than a conventional mortgage. If you've recently received an inheritance and earn income through foreign dividends, you may already have the financial resources needed to qualify. However, lenders look very closely at the source, stability, and documentation of both. Understanding the requirements for jumbo loan with recent inheritance for down payment and foreign dividend income can make the difference between a smooth approval and an unexpected denial. This guide walks you through what lenders typically expect, how to present your assets and income correctly, and what steps you can take to strengthen your application.
What Makes Jumbo Loans Different From Conventional Mortgages
A jumbo loan is a mortgage that exceeds the conforming loan limits set by the Federal Housing Finance Agency (FHFA). In most parts of the United States, any loan above approximately $766,550 (as of recent guidelines) is considered a jumbo loan, though this threshold may be higher in designated high-cost areas. Because jumbo loans aren't backed by Fannie Mae or Freddie Mac, lenders take on the full credit risk themselves.
This is why jumbo lenders tend to apply stricter qualification standards. You'll typically need a higher credit score, a lower debt-to-income (DTI) ratio, and more substantial cash reserves than what's required for a conforming loan. Lenders also scrutinize income sources more carefully, which is especially relevant when income comes from non-traditional sources like foreign dividend income.
- Credit score: Most lenders prefer a score of 700 or higher, with many requiring 720 or above for the best terms.
- Debt-to-income ratio: A DTI below 43% is often preferred, though requirements can vary by lender.
- Cash reserves: Lenders may require 6 to 12 months of mortgage payments held in liquid assets after closing.
- Down payment: Jumbo loans commonly require 10% to 20% or more, depending on the loan amount and lender policies.
When your down payment comes from an inheritance or your qualifying income includes foreign dividends, lenders will need to verify and document these sources thoroughly before issuing approval.
Using an Inherited Down Payment: What Lenders Need to See
Receiving an inheritance can be a meaningful financial opportunity, especially when you're looking to purchase a high-value property. But using inherited funds as a down payment on a jumbo loan comes with documentation requirements that many borrowers don't anticipate. Lenders need to confirm that the funds are legitimate, that they've been properly received, and that they aren't a disguised loan that would affect your DTI ratio.
Paper Trail and Sourcing Requirements
For inherited funds, lenders will typically require a clear paper trail showing the origin of the money. This often includes a copy of the probate court documents or the will showing your right to the inheritance, a letter from the estate attorney or executor confirming the disbursement, and bank statements showing the deposit of funds into your account. If the inheritance came in the form of stocks, bonds, or other assets that were then liquidated, you may also need brokerage account statements documenting the sale and subsequent transfer.
Seasoning of Inherited Funds
One important consideration is how recently you received the inheritance. Many jumbo lenders prefer — and sometimes require — that inherited funds be "seasoned," meaning they've been sitting in your bank account for at least 60 to 90 days. Funds that have been in your account for several months are generally easier to document because they simply appear as part of your current asset base. Freshly deposited inherited funds may require additional explanation and supporting documents. If your inheritance was received very recently, it's a good idea to speak with a lender early in the process to understand their specific seasoning policies.
Gift Funds vs. Inherited Funds
It's worth noting that inherited funds are generally treated differently from gift funds by lenders. Inherited money is typically considered your own asset, while gift funds from a living donor may require a gift letter confirming no repayment is expected. Be sure to communicate clearly with your lender about whether funds came from an estate versus a living relative, as the documentation process may differ.
How Foreign Dividend Income Is Evaluated for Jumbo Loan Qualification
Foreign dividend income — earnings from stocks, mutual funds, or investment holdings based outside the United States — can be a legitimate qualifying income source for a jumbo mortgage. However, lenders approach it with extra caution due to currency risk, the complexity of foreign financial disclosures, and the challenge of verifying consistency.
Consistency and History of Income
Most jumbo lenders want to see a two-year history of receiving foreign dividend income before they'll consider it for qualification purposes. They'll typically average the income over that period and use that figure in your DTI calculation. If the income has been declining year over year, lenders may use the lower figure or decline to count it altogether. Consistency and an upward or stable trend are key factors in how this income is viewed.
Documentation Requirements
Documenting foreign dividend income for a jumbo loan typically requires the following:
- Two years of federal tax returns (U.S. Form 1040) with all foreign income reported, including any Form 1116 for foreign tax credits
- Foreign brokerage account statements translated into English, if applicable
- Bank statements showing the deposit of dividend payments into a U.S. or accessible bank account
- A letter from the foreign brokerage or financial institution confirming the ongoing nature of the income, if available
If you hold assets in a foreign country and receive dividends that are not reported on your U.S. tax return, this could create additional complications. Lenders generally require that income be properly documented on U.S. tax returns to be eligible for use in qualifying. Working with a CPA experienced in international taxation may help ensure your foreign income is reported correctly and in a way that supports your mortgage application.
Currency Conversion and Stability Concerns
Lenders may also apply additional scrutiny to foreign dividend income because of exchange rate fluctuations. A lender might discount the income or apply a conservative conversion rate when calculating your qualifying income. Some lenders may require that the income be converted to U.S. dollars based on a specific period's average exchange rate. It's worth asking your lender exactly how they handle foreign currency income to avoid surprises during underwriting.
Key Requirements for Jumbo Loan with Recent Inheritance for Down Payment and Foreign Dividend Income
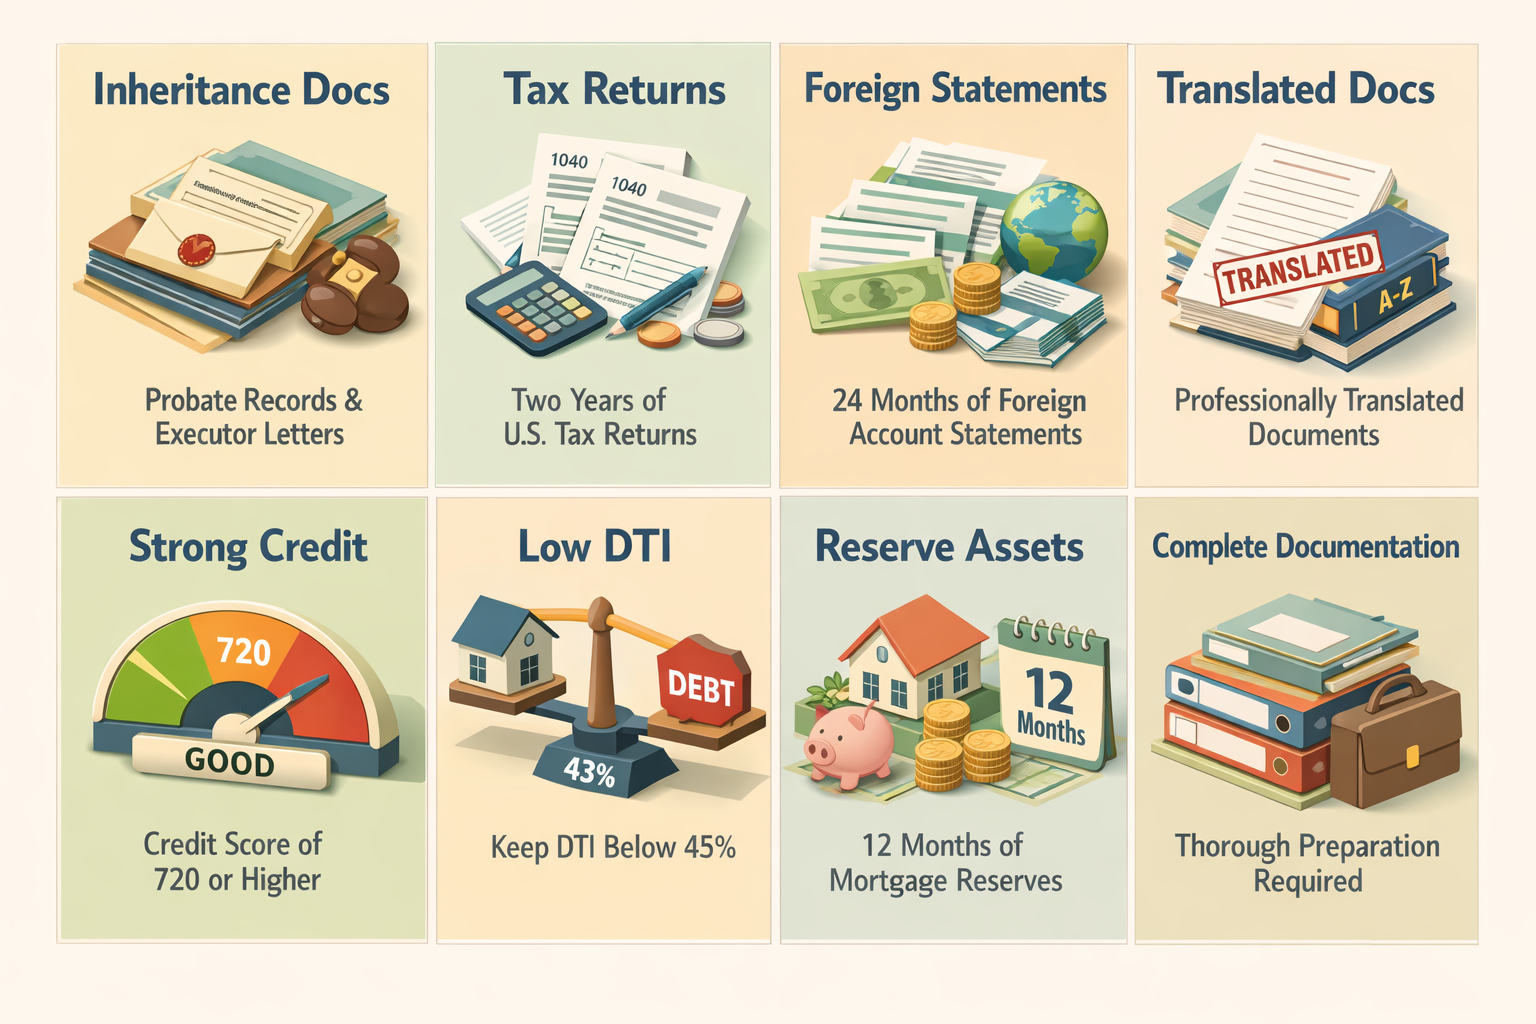
When you combine a recently received inheritance with foreign dividend income in a jumbo loan application, the documentation and verification requirements compound. Lenders are dealing with two non-standard elements simultaneously, which often means more underwriting scrutiny and longer processing timelines. Here's a consolidated view of what you should prepare:
- Complete inheritance documentation: Probate records, executor letters, bank statements showing receipt of funds, and any applicable liquidation statements if assets were sold.
- Two years of U.S. tax returns: Including all foreign income schedules, foreign tax credit forms, and any FBAR (FinCEN Form 114) filings if required for foreign financial accounts.
- Foreign account statements: At least 24 months of statements from foreign brokerage or financial accounts showing dividend payment history.
- Translated documents: Any documents not in English should be professionally translated.
- Strong credit profile: A credit score of 720 or higher is often recommended for jumbo loans with complex income scenarios.
- Low DTI ratio: With non-standard income, keeping your DTI well below 43% may help offset lender concerns.
- Reserve assets: Demonstrating 12 or more months of mortgage reserves after closing can significantly strengthen your application.
The requirements for jumbo loan with recent inheritance for down payment and foreign dividend income are manageable when you approach the process with thorough preparation and transparent communication with your lender or mortgage broker.
Choosing the Right Lender for a Complex Jumbo Application
Not all lenders are equally equipped to handle jumbo loans with complex income and asset profiles. Portfolio lenders — institutions that keep loans on their own books rather than selling them to the secondary market — often have more flexibility in how they evaluate non-traditional income sources like foreign dividends and inherited assets. Some private banks and wealth management-affiliated lenders may also be more comfortable with international financial profiles.
Working with a mortgage broker who specializes in jumbo and non-QM (non-qualified mortgage) products can be particularly valuable in these situations. A knowledgeable broker can match your financial profile with the lenders most likely to view your application favorably, potentially saving you time and reducing the risk of unnecessary credit inquiries from multiple applications.
When evaluating lenders, consider asking the following questions:
- Do you have experience underwriting loans with foreign dividend income?
- What is your seasoning requirement for inherited funds used as a down payment?
- How do you handle currency conversion for foreign income sources?
- Do you offer bank statement or asset depletion programs as an alternative qualification method?
Some lenders may offer asset depletion programs, where your total liquid assets — including inherited funds and foreign investments — are divided over a set period to create a qualifying monthly income figure. This could be a useful alternative if your foreign dividend income doesn't meet standard documentation requirements.
Strengthening Your Application Before You Apply
Preparation is everything when applying for a jumbo loan with a complex financial profile. Taking proactive steps before submitting your application can meaningfully improve your chances of jumbo loan approval and help you secure more favorable loan terms.
Work With a CPA Familiar With International Income
If your foreign dividend income hasn't been consistently reported on your U.S. tax returns, now is the time to address that. A CPA with experience in international taxation can help ensure your returns are accurate, complete, and structured in a way that clearly documents your income history. This could involve amending prior returns or filing appropriate foreign financial account disclosures.
Allow Inherited Funds Time to Season
If possible, give your inherited funds time to sit in your account before applying. The longer the funds are present in your bank statements, the less documentation lenders may require to source them. In some cases, waiting an additional 30 to 60 days before applying could simplify the underwriting process considerably.
Build or Maintain Strong Credit
Pay down existing debts where possible and avoid opening new credit accounts in the months leading up to your application. A strong credit score combined with a solid asset base gives lenders greater confidence when evaluating a complex financial profile.
Organize All Foreign Financial Documents
Gather your foreign brokerage statements, dividend income records, and any relevant correspondence well in advance. If documents are in a foreign language, arrange for professional translation early. Delays caused by missing or untranslated documents are one of the most common reasons complex jumbo applications take longer to process.
●Conclusion
Qualifying for a jumbo loan when your down payment comes from a recent inheritance and your income includes foreign dividends is absolutely achievable — but it does require careful planning and thorough documentation. Lenders want to see a clear picture of where your money comes from, how stable your income is, and that you have the financial depth to manage a large mortgage responsibly. By understanding the requirements for jumbo loan with recent inheritance for down payment and foreign dividend income, organizing your paperwork early, and partnering with the right lender or mortgage professional, you can approach this process with confidence. At LoanWise, we're here to help you navigate complex mortgage scenarios and connect you with financing solutions that fit your unique financial profile. Reach out to our team today to explore your options.