As housing costs continue to rise across the country, more homebuyers are exploring creative living and ownership arrangements to make homeownership a reality. One growing trend is the shared equity co-housing model, where two or more individuals or households share ownership and sometimes living space under one roof. If you're considering this path, you may be wondering whether an FHA loan can help you get there. The good news is that qualifying for FHA loan with shared equity co-housing arrangement is possible — but it does come with specific guidelines that both buyers and lenders must carefully follow. This guide breaks down what you need to know before you apply.
What Is a Shared Equity Co-Housing Arrangement?
A shared equity co-housing arrangement is a housing model in which multiple parties hold an ownership interest in the same property. This could mean two friends purchasing a home together, a nonprofit organization partnering with a buyer to reduce purchase costs, or a community land trust helping a lower-income household afford a home by retaining a portion of the property's equity.
Co-housing arrangements can take many forms. In some cases, all owners live in the home together. In others, one party occupies the property while the other holds a financial or equity stake without residing there. The structure of the agreement — including how equity is split, how expenses are shared, and what happens upon sale — can vary significantly from one arrangement to the next.
These setups are becoming increasingly popular among first-time homebuyers, multigenerational families, and community-focused housing programs. Understanding how the FHA views these arrangements is the first step toward securing financing.
How the FHA Views Co-Housing and Shared Ownership
The Federal Housing Administration (FHA) insures loans made by approved lenders, allowing borrowers to access FHA financing with lower down payments and more flexible credit requirements than many conventional loans. However, FHA loans come with strict guidelines that govern who can borrow, how properties must be used, and how ownership agreements may be structured.
When it comes to shared equity arrangements, the FHA generally focuses on a few key concerns. First and foremost is the owner-occupancy requirement. FHA loans are intended for primary residences, meaning at least one borrower on the loan must intend to live in the home as their principal place of residence. This rule is non-negotiable and applies regardless of the co-housing structure.
The FHA also pays close attention to the terms of any shared equity agreement, particularly if a nonprofit, employer, or community land trust is involved. Certain shared equity programs may qualify under FHA guidelines, but the agreement must meet specific conditions related to resale restrictions, equity sharing terms, and the financial standing of the partner organization.
FHA Loan Co-Housing Requirements Every Borrower Should Know
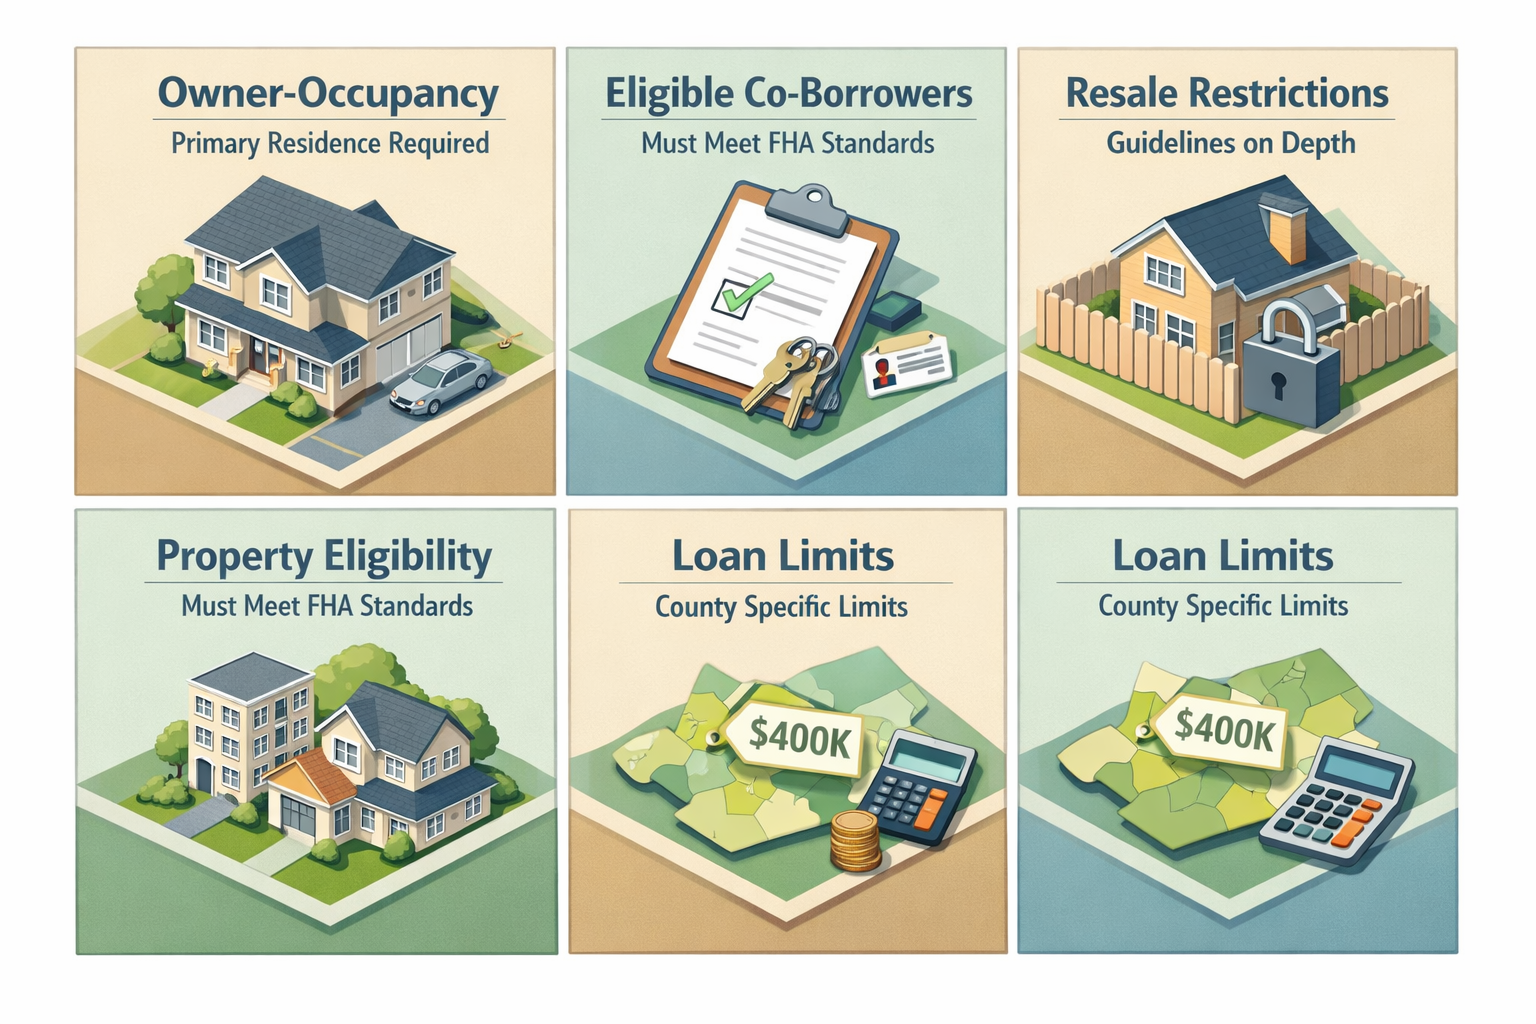
Understanding the FHA loan co-housing requirements is essential before you move forward with an application. Here are the primary factors lenders and underwriters will evaluate:
- Owner-Occupancy: At least one borrower listed on the FHA loan must occupy the property as their primary residence. Co-housing arrangements where all parties plan to rent or use the home as an investment property are not eligible for FHA financing.
- Eligible Co-Borrowers: The FHA allows non-occupying co-borrowers in some cases, but these individuals must still meet FHA credit and income requirements. Their financial profile will be evaluated alongside the primary borrower's.
- Resale Restrictions: If a community land trust or nonprofit holds a shared equity stake with resale restrictions, the FHA has specific guidelines on how deep those restrictions can go. Overly restrictive resale clauses could disqualify a property from FHA financing.
- Property Eligibility: The home itself must meet FHA minimum property standards. This is especially important in co-housing communities where shared spaces, utilities, or structures may require additional review.
- Loan Limits: FHA loan limits vary by county, and the purchase price — including any equity contribution from a partner — must fall within the applicable limit for the area.
Meeting these requirements doesn't guarantee approval, but it does set the foundation for a stronger application. Working with an FHA-approved lender who has experience in shared equity arrangements can make a significant difference in navigate the approval process.
Qualifying for FHA Loan with Shared Equity Co-Housing Arrangement: Credit and Income Standards
Beyond the structural requirements of the co-housing arrangement itself, each borrower listed on the loan must individually satisfy FHA credit and income standards. These standards are generally more accessible than conventional loan benchmarks, which is part of what makes FHA financing attractive for buyers in shared equity programs.
From a credit standpoint, the FHA typically requires a minimum credit score of 580 for borrowers seeking the standard 3.5% down payment. Borrowers with scores between 500 and 579 may still qualify, but they'll likely need to put down at least 10%. Credit history, outstanding debts, and any prior derogatory marks will all factor into the lender's decision.
Income qualification in a shared equity scenario can be both an advantage and a complexity. If multiple co-borrowers are listed on the loan, their combined income may be used to meet debt-to-income (DTI) ratio requirements. The FHA generally looks for a DTI ratio at or below 43%, though some lenders may accept higher ratios with compensating factors such as strong cash reserves or a solid credit history.
It's worth noting that income from a co-housing partner who is not listed on the loan typically cannot be counted toward qualification. This means the borrowing party must be able to demonstrate sufficient income on their own — or with listed co-borrowers — to support the monthly mortgage payment.
Community Land Trusts and Nonprofit Equity Partners Under FHA Guidelines
One of the most common forms of shared equity co-housing involves community land trusts (CLTs) or nonprofit organizations that partner with homebuyers. These programs are designed to preserve affordable homeownership by retaining a portion of the property's equity, often in exchange for keeping resale prices below market rate.
The FHA does recognize certain CLT arrangements and has issued guidance allowing FHA-insured loans on properties with ground leases — a common structure used by land trusts. However, the ground lease must meet specific FHA requirements. These may include minimum lease terms, provisions for lender notification in the event of default, and restrictions on the depth of resale limitations.
If you're working with a nonprofit equity partner or a community land trust, it's important to confirm upfront that the organization's structure and agreement terms are compatible with FHA financing. Not all CLT agreements automatically qualify, and gaps in compliance could delay or derail your loan approval. Ask the organization directly whether they have experience closing FHA loans, and request documentation that confirms their program's eligibility.
Practical Tips to Strengthen Your FHA Application in a Co-Housing Scenario
If you're serious about qualifying for FHA loan with shared equity co-housing arrangement, a proactive approach to your application can help things move more smoothly. Here are some practical strategies:
- Work with an experienced FHA lender: Not all FHA lenders have handled shared equity or co-housing transactions. Seek out a lender with demonstrated experience in these arrangements. They'll know what documentation is required and how to present your file to underwriting.
- Get the co-housing agreement reviewed: Have an attorney review the shared equity agreement before submitting it as part of your loan package. The terms must be clearly defined and compliant with FHA guidelines.
- Document all income sources carefully: Gather pay stubs, tax returns, W-2s, and any other income documentation for all borrowers listed on the loan. Thorough documentation can help offset any complexity introduced by the co-housing structure.
- Maintain a clean credit profile: In the months leading up to your application, avoid taking on new debt, making large purchases, or missing any bill payments. A stable credit profile signals reliability to underwriters.
- Check property eligibility early: Before falling in love with a particular home or co-housing community, confirm that the property meets FHA minimum standards. An FHA appraisal will evaluate both value and condition.
- Communicate with all co-owners: Make sure everyone involved in the co-housing arrangement understands their role in the mortgage process and is prepared to provide any documentation required by the lender.
●Conclusion
Shared equity co-housing arrangements offer a creative and often more affordable path to homeownership — and the FHA loan program may be able to help you get there. While the process involves navigating some unique requirements around occupancy, agreement structure, and property eligibility, it's certainly achievable with the right guidance and preparation. The key is understanding the rules, working with knowledgeable professionals, and approaching your application with thorough documentation and realistic expectations. At LoanWise, we're here to help you explore your financing options and find the right loan for your situation. If you're considering a co-housing arrangement, reach out to one of our FHA-experienced loan specialists today to start the conversation.