Running an art gallery is a labor of love — but it's also a business with real financial demands. If your gallery sees most of its foot traffic and sales during peak seasons, you already know how tough the quiet months can be. Payroll, rent, utilities, insurance, and inventory costs don't pause just because the crowds do. That's where understanding how to get a working capital loan for a seasonal art gallery during off-season becomes genuinely valuable. This article breaks down your financing options, what lenders typically look for, and practical steps you can take to strengthen your application — even when revenue is temporarily low.
Why Seasonal Art Galleries Face Unique Cash Flow Challenges
Art galleries are often tied to tourism cycles, local events, holiday shopping seasons, or regional art fairs. A coastal gallery might thrive from spring through early fall, while an urban gallery may peak around the holiday gift-buying season or during local arts festivals. Outside of those windows, revenue can drop sharply — sometimes dramatically.
This seasonality creates a cash flow gap that many small business owners struggle to navigate. Fixed overhead costs remain steady while income slows. Without a financial cushion or a reliable funding source, even a well-established gallery could find itself unable to cover basic operating expenses.
Common off-season financial pressures for art gallery owners include:
- Ongoing rent and utilities for gallery space
- Staff wages for part-time or full-time employees
- Marketing and promotion costs to build buzz for the next peak season
- Inventory acquisition — purchasing or commissioning artwork ahead of busy periods
- Insurance premiums and licensing fees
Recognizing these pressures early gives you a real advantage when it's time to approach a lender. The more clearly you can demonstrate your seasonal pattern and your plan to bridge the gap, the more seriously a lender may take your application.
What Is a Working Capital Loan and How Does It Work for Art Galleries
A working capital loan is a type of short-term business financing designed to cover everyday operational expenses rather than long-term assets or capital investments. Unlike equipment loans or commercial real estate financing, working capital loans are typically used for cash flow management — keeping the lights on and the business moving during lean periods.
For a seasonal art gallery, a working capital loan could help you:
- Pay staff during months when sales are slow
- Cover gallery rent without dipping into personal savings
- Fund a marketing campaign ahead of the next peak season
- Purchase new artwork or commission pieces in advance
- Handle unexpected repairs or operational costs
These loans are generally repaid over a shorter term — often ranging from a few months to a couple of years — and may come with fixed or variable interest rates depending on the lender and loan type. Some working capital products, like a business line of credit, allow you to draw funds as needed and only pay interest on what you use, which can be especially practical for seasonal businesses.
It's worth noting that terms, rates, and eligibility requirements vary widely across lenders. What one lender offers a gallery with three years of operating history may look quite different from what another offers a newer business. Comparing multiple options is always a smart move.
Exploring the Right Loan Types for Off-Season Gallery Funding
Not every loan product is suited to the rhythms of a seasonal art gallery. Understanding the landscape of available options can help you choose the most appropriate financing structure for your situation.
Business Line of Credit
A business line of credit is one of the most flexible options for seasonal businesses. You're approved for a maximum credit limit and can draw from it as needed — paying interest only on the amount you've used. During the off-season, you might draw funds to cover expenses, then repay as peak-season revenue flows in. This revolving structure can make it a practical fit for galleries with predictable seasonal cycles.
Short-Term Business Loans
A short-term term loan delivers a lump sum upfront, which you repay over a defined period with interest. This could work well if you have a specific, one-time off-season expense — like a major gallery renovation or a large art acquisition — and you know exactly how much you need.
SBA Loans
The U.S. Small Business Administration (SBA) offers several loan programs that small business owners may find accessible. The SBA 7(a) loan is the most common and can be used for working capital purposes. While SBA loans often come with competitive rates and longer repayment terms, the application process may take longer and require more documentation than alternative lenders. If time is a factor, this may or may not be the right fit depending on your situation.
Merchant Cash Advance
A merchant cash advance (MCA) provides upfront funding in exchange for a percentage of future sales. For galleries that process a significant volume of card transactions during peak seasons, this could be an option — though MCAs often carry higher effective costs than traditional loans and should be evaluated carefully before committing.
SBA Microloans
If your gallery is smaller or newer, an SBA microloan — which typically offers up to $50,000 — might be worth exploring. These are designed for small businesses and startups, and the funds can often be used for working capital.
How to Get a Working Capital Loan for a Seasonal Art Gallery During Off-Season: Step-by-Step
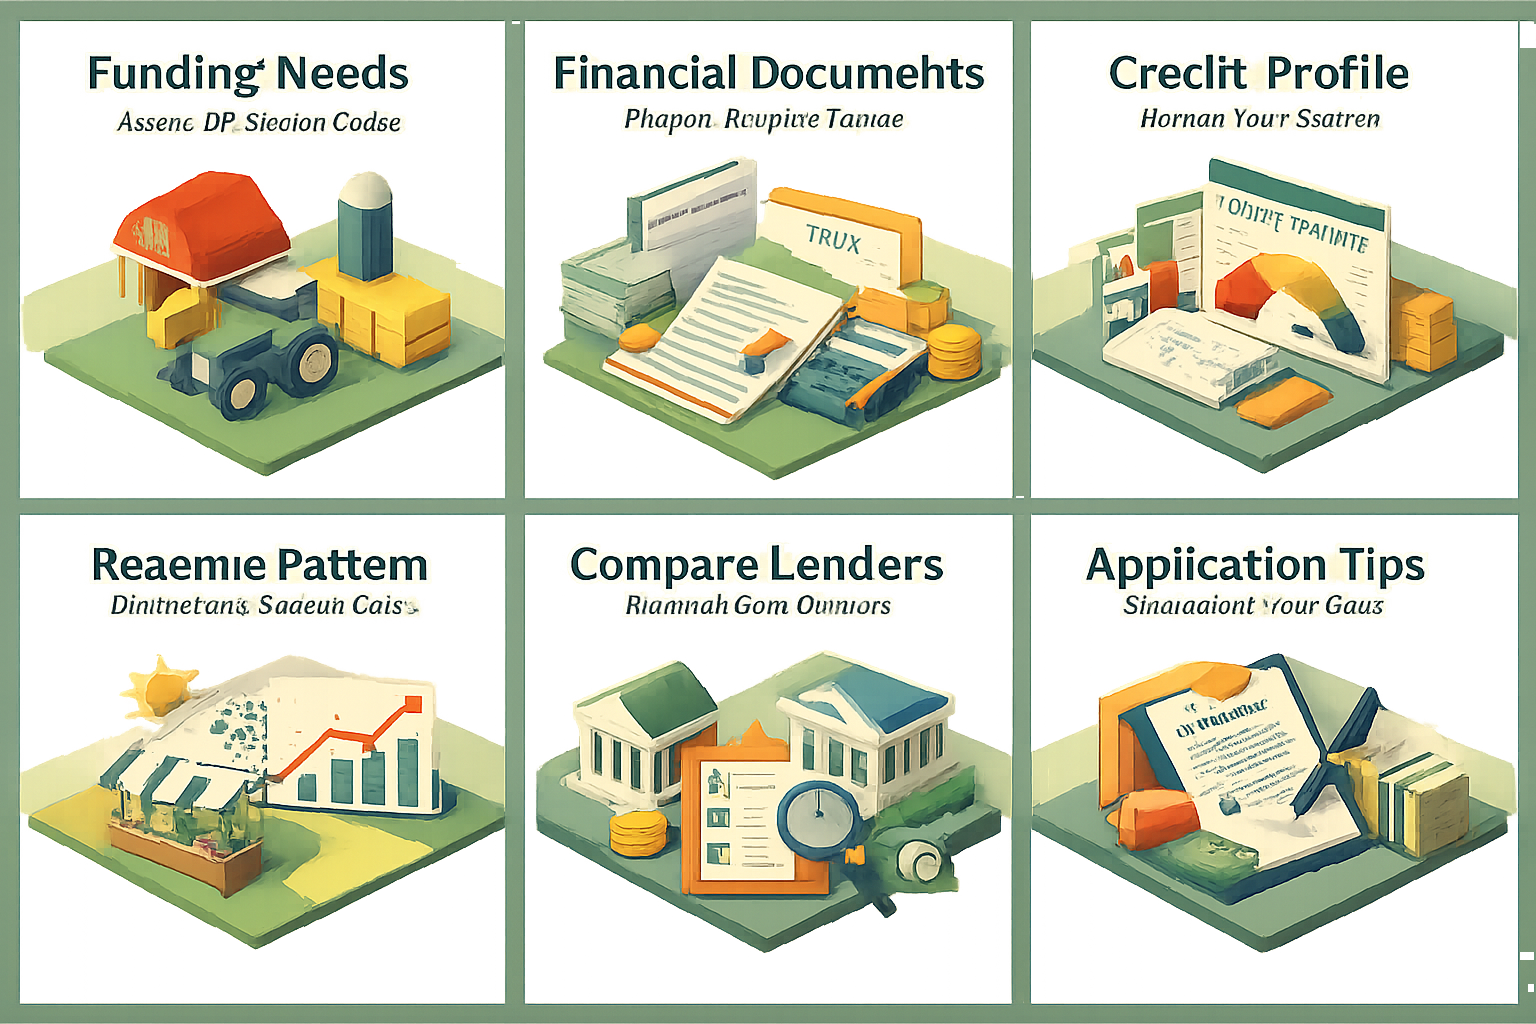
Knowing how to get a working capital loan for a seasonal art gallery during off-season means more than just filling out an application. Lenders want to see that your business is financially responsible and that your seasonal model is predictable and manageable. Here's a practical approach:
Step 1: Assess Your Funding Needs
Before approaching any lender, get clear on how much you actually need. Review your off-season operating costs in detail — rent, payroll, utilities, inventory, and marketing — and calculate the funding gap. Borrowing too little may leave you short; borrowing too much adds unnecessary interest costs.
Step 2: Gather Your Financial Documents
Most lenders will ask for some combination of the following:
- Business bank statements (typically 3–12 months)
- Profit and loss statements
- Tax returns (business and sometimes personal)
- A basic business plan or cash flow projection
- Proof of business ownership and legal documents
Having these ready in advance can speed up your application significantly.
Step 3: Review Your Business Credit Profile
Lenders will typically pull your business credit score and may also look at your personal credit. A stronger credit profile generally leads to better loan terms. If your scores need improvement, it may be worth taking a few months to pay down existing balances, correct errors on your credit report, and avoid opening new accounts before applying.
Step 4: Demonstrate Your Seasonal Revenue Pattern
One of the most powerful things you can do as a seasonal business is show lenders your revenue cycle clearly. Use bank statements and financial records to illustrate that your slow months are predictable and temporary — not a sign of business decline. Showing that peak-season revenue reliably covers repayment can meaningfully strengthen your application.
Step 5: Compare Lenders and Loan Products
Don't settle for the first offer you receive. Compare banks, credit unions, online lenders, and SBA-approved lenders. Pay attention to the annual percentage rate (APR), repayment terms, fees, and prepayment penalties. A lower interest rate with a short repayment window might not serve a seasonal business as well as a slightly higher rate with more flexible timing.
What Lenders Look for When Evaluating Seasonal Business Applications
Understanding the lender's perspective can help you craft a stronger application. While requirements vary, most lenders evaluating a seasonal art gallery will consider several key factors.
Time in Business
Many lenders prefer businesses that have been operating for at least one to two years. This gives them enough historical data to assess your seasonal patterns. Newer galleries may face more scrutiny and could benefit from exploring SBA microloans or alternative online lenders with more flexible eligibility thresholds.
Annual Revenue
Lenders typically want to see sufficient annual revenue to support loan repayment. Even if monthly revenue fluctuates significantly due to seasonality, your total annual figures matter. Keep in mind that some online lenders may have lower revenue minimums than traditional banks.
Cash Flow Consistency
Consistent cash flow — even with seasonal peaks and valleys — is a positive signal. Lenders want to know that money is reliably coming into the business and that you have a history of managing expenses responsibly during slow periods.
Collateral
Some lenders may require collateral to secure a working capital loan, especially for larger amounts. This could include business assets, inventory, or in some cases personal assets. Unsecured loans are available but may come with higher rates or lower limits.
Owner's Personal Credit
For small businesses, especially sole proprietorships or smaller LLCs, the owner's personal credit score often plays a meaningful role in the lending decision. Maintaining a healthy personal credit score is a useful habit for any small business owner.
Practical Tips to Strengthen Your Loan Application as an Art Gallery Owner
Beyond the basics, there are several strategies that could help you present a more compelling case to potential lenders.
- Open a dedicated business bank account if you haven't already. Mixing personal and business finances can make it harder for lenders to evaluate your business cash flow.
- Build a business credit history by using a business credit card responsibly and paying suppliers on time. This helps establish a credit profile separate from your personal history.
- Prepare a simple cash flow forecast showing projected income and expenses for the coming 12 months. Even a basic spreadsheet can demonstrate that you've thought through your off-season strategy.
- Write a brief narrative explaining your seasonal model. A short, clear explanation of your gallery's revenue cycle — why it peaks, how you manage the slow months, and how you plan to use and repay the loan — can make a real difference.
- Establish banking relationships early. If you have an existing relationship with a bank or credit union, that familiarity may work in your favor when applying for financing.
- Consider applying before the off-season begins. Applying when your business is still generating revenue — rather than waiting until you're already in financial stress — typically puts you in a stronger position.
These steps won't guarantee approval, but they can meaningfully improve your chances and potentially help you secure more favorable terms.
●Conclusion
Managing a seasonal art gallery takes creativity, passion, and smart financial planning. The off-season doesn't have to feel like a financial crisis — it can be a planned, well-funded pause that sets you up for a stronger peak season ahead. By understanding working capital loan seasonal art gallery options and taking deliberate steps to prepare your application, you put yourself in a much better position to secure the funding you need. Whether you choose a business line of credit, an SBA loan, or a short-term term loan, the key is to start planning early, know your numbers, and work with lenders who understand the unique nature of seasonal businesses. LoanWise is here to help you explore your options and find the financing solution that fits your gallery's rhythm. Reach out today to get started.