More homeowners are turning their detached garages into livable spaces — think guest suites, rental units, or home offices. It's a smart way to add value and functionality to a property. But when it's time to borrow against that equity through a Home Equity Line of Credit, things can get a little more complex. Understanding HELOC requirements for property with existing detached garage conversion is essential before you apply, because lenders evaluate these properties differently than standard single-family homes. From how the converted space is appraised to whether local zoning approves the use, several factors influence your eligibility, your credit limit, and your interest rate. This guide walks you through what you need to know so you can approach lenders with confidence.
What Is a HELOC and How Does It Work for Homeowners
A Home Equity Line of Credit — commonly called a HELOC — is a revolving credit line secured by the equity in your home. Think of it like a credit card, but backed by your property. Lenders typically allow you to borrow up to a certain percentage of your home's appraised value, minus what you still owe on your mortgage. This percentage, known as the combined loan-to-value ratio or CLTV, often falls somewhere between 80% and 90%, though it may vary by lender and market conditions.
During the draw period, which usually lasts around five to ten years, you can borrow funds, repay them, and borrow again as needed. After the draw period ends, you enter the repayment phase, where you pay back the remaining balance — often over ten to twenty years. Because a HELOC is tied to your home's value, any factor that affects how your property is appraised will directly influence how much you can access.
For homeowners with a converted detached garage, this connection between property value and borrowing power becomes especially important. The way lenders and appraisers view your converted space could either increase or limit the home equity available to you.
How a Detached Garage Conversion Affects Your Property's Value
A garage conversion — particularly a detached one — can meaningfully change how your property is valued, but the outcome depends heavily on several variables. When an appraiser visits your home, they'll assess the converted structure based on its permitted use, quality of construction, and how comparable properties in your area are valued. If the conversion was done with proper permits and meets local building codes, it's more likely to be counted as usable square footage, which could boost your home's appraised value.
On the other hand, if the garage was converted without permits — sometimes called an unpermitted conversion — appraisers may not be able to include that space in the home's livable square footage. In some cases, they might even flag it as a potential liability, which could actually reduce your appraised value or complicate the lending process.
It's also worth noting that detached structures are typically appraised differently than attached spaces. While a converted detached garage may function as an accessory dwelling unit or ADU, not all lenders treat ADUs the same way. Some may count projected rental income toward your qualifying income, while others may not — which can affect both your loan eligibility and your maximum credit line.
- Permitted conversions are far more likely to be counted as livable square footage by appraisers.
- Unpermitted conversions may be excluded from the valuation or flagged by underwriters.
- Quality of construction matters — finishes, insulation, and utility connections all influence value.
- Local comparable sales (comps) with similar ADU or converted structures will shape the final number.
Zoning, Permits, and Legal Status: What Lenders Really Want to See
One of the most critical aspects of understanding HELOC requirements for property with existing detached garage conversion is knowing what documentation lenders expect. Before approving a HELOC, most lenders will want to confirm that the converted space is legally recognized. This typically means verifying that the conversion received the appropriate building permits, passed inspections, and is consistent with the local zoning classification for your property.
Zoning laws vary significantly by city and county. Some municipalities have actively encouraged ADU development by relaxing zoning restrictions, while others maintain strict rules about how detached structures can be used. If your converted garage is being used as a separate dwelling unit — even informally — but your zoning doesn't allow for it, this could create complications during underwriting.
Here's what lenders may typically review when evaluating a property with a detached garage conversion:
- Building permits: Evidence that the conversion was reviewed and approved by the local authority.
- Certificate of occupancy: Confirms the space is legally habitable and meets safety standards.
- Zoning classification: Verifies the property's land use aligns with local codes.
- Property tax records: May reflect whether the converted space has been officially recognized and assessed.
- Title report: Ensures there are no encumbrances or code violations attached to the property.
If you're unsure about your property's status, it's worth reaching out to your local planning or building department before applying for a HELOC. Addressing any outstanding permit issues ahead of time could significantly smooth the approval process.
Key Borrower Qualification Criteria for a HELOC on a Converted Property
Beyond the property itself, lenders will evaluate you as a borrower. The qualification criteria for a HELOC on a property with a detached garage conversion are largely the same as those for any standard HELOC, though the property-specific complexities may lead some lenders to apply additional scrutiny.
Here are the core factors lenders typically assess:
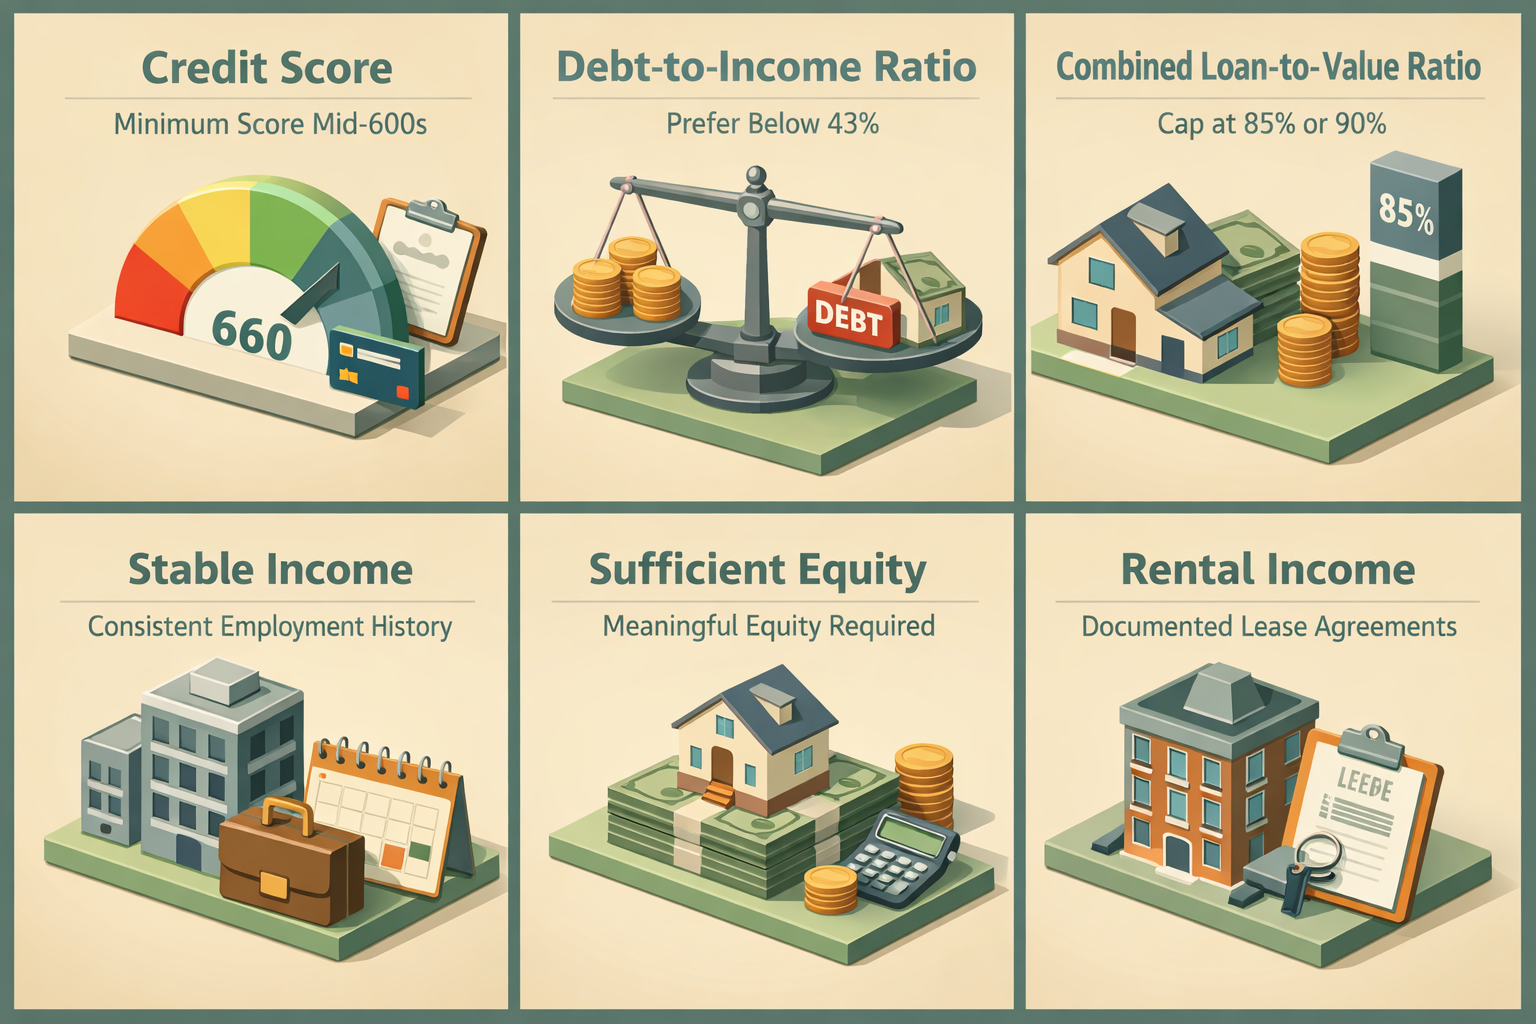
- Credit score: Most lenders look for a minimum score in the mid-600s, though higher scores — often 700 or above — tend to unlock better rates and higher credit limits. A strong credit history signals that you're a reliable borrower.
- Debt-to-income ratio (DTI): This compares your monthly debt obligations to your gross monthly income. Lenders generally prefer a DTI below 43%, though some may allow slightly higher ratios depending on other compensating factors.
- Combined loan-to-value ratio (CLTV): This is the total of all mortgages and the new HELOC compared to the property's appraised value. Many lenders cap this at 85% or 90%, so if your home hasn't appreciated significantly or if the conversion reduced your appraised value, you may have less equity to draw from.
- Stable income: Consistent employment history and verifiable income give lenders confidence in your ability to repay. If you're renting out the converted space, some lenders may consider that rental income, though documentation — like a signed lease — is usually required.
- Sufficient equity: You'll need meaningful equity built up in your home. The more equity you have, the more flexibility you're likely to have in terms of your credit line size and terms.
It's also worth knowing that if your converted detached garage is functioning as a rental unit, some lenders may classify your property differently — potentially as a two-unit property — which could shift which loan programs apply to your situation.
The Appraisal Process for Homes with Detached Accessory Dwelling Units
The appraisal is one of the most influential steps in the HELOC process, especially when a detached accessory dwelling unit is involved. Lenders order an appraisal to establish how much your home is currently worth — and that number directly determines how much you can borrow.
For a standard home, understanding how appraisals work is key: appraisers typically compare your property to three to five similar recently sold homes in your area, adjusting for differences in size, condition, and features. When a detached converted garage or ADU is part of the equation, the appraiser will try to find comps that also include similar structures. In neighborhoods where ADUs are common, this is more straightforward. In areas where they're rare, finding good comps can be challenging, and the appraiser may need to make larger adjustments — which can introduce more uncertainty into the final value.
A well-documented, permitted conversion that adds functional living space — such as a studio apartment with a kitchen and bathroom — is more likely to contribute positively to the appraised value than a minimally finished room. Appraisers may also consider the income potential of the space if it's being rented, particularly in markets where rental demand is strong.
To help the appraisal go smoothly, consider gathering the following before the appraiser visits:
- Copies of all building permits and inspection records for the conversion
- Any certificates of occupancy related to the detached structure
- A current lease agreement if the space is being rented
- Documentation of any recent improvements or upgrades to the converted space
Lender Options and What to Expect During the Application Process
Not all lenders are equally comfortable with properties that include detached garage conversions or ADUs. Some traditional banks and credit unions may have stricter guidelines, while certain portfolio lenders — those who keep loans on their own books rather than selling them — may offer more flexibility. Shopping around is genuinely important here, as one lender's hesitation doesn't necessarily reflect the market as a whole.
When you apply for a HELOC on a property with a converted detached garage, the general process looks something like this:
- Pre-application review: Gather your financial documents, property records, and permit history. A preliminary conversation with a loan officer can help you understand whether your property fits a lender's guidelines before you formally apply.
- Application submission: You'll provide income verification, tax returns, bank statements, and information about existing mortgages or liens on the property.
- Appraisal: The lender will order an appraisal to determine your home's current market value, factoring in the converted structure.
- Underwriting: The lender's underwriting team will review your financial profile alongside the property details, including its legal status and how the conversion is documented.
- Approval and closing: If everything checks out, you'll receive an approval, review your terms, and sign closing documents. The HELOC account is then opened for use.
Keep in mind that the timeline can vary depending on appraisal scheduling, underwriting workloads, and how quickly you can supply requested documents. Being organized and proactive can help keep things moving.
Practical Steps to Strengthen Your HELOC Application on a Converted Property
If you're serious about tapping your home equity through a HELOC, there are practical steps you can take to put yourself in the best position possible — especially when your property includes a detached garage conversion.
Resolve any permit issues first. If your conversion was done without permits, look into your municipality's amnesty or retroactive permit programs. Some local governments offer pathways to legalize unpermitted ADUs, which could significantly improve your approval odds and appraised value.
Review your credit report. Before applying, pull your credit report and look for any errors or outstanding issues. Disputing inaccuracies and paying down revolving balances can improve your score, which may qualify you for better HELOC terms.
Calculate your equity realistically. Use your current mortgage balance and a conservative estimate of your home's value to get a rough sense of your available equity. Remember that lenders will limit total borrowing to a percentage of appraised value, so setting realistic expectations early can save time.
Document the rental income. If you're renting out the converted space, maintain clear records — signed leases, payment history, and bank deposit documentation. This income may help strengthen your debt-to-income profile, depending on the lender's guidelines.
Compare multiple lenders. Rates, fees, draw period lengths, and property eligibility guidelines vary from lender to lender. Getting quotes from at least two or three institutions gives you a clearer picture of what's available and may surface a lender who's more comfortable with your specific property type.
Understanding HELOC requirements for property with existing detached garage conversion takes a bit of preparation, but homeowners who do their homework are in a much stronger position to secure the financing they need.
●Conclusion
Navigating a HELOC on a property with a detached garage conversion isn't quite like a standard home equity application — but it's absolutely achievable with the right preparation. The converted space can be a genuine asset, both as a source of added home value and as a potential income generator. The key is making sure everything is properly permitted, documented, and presented clearly to lenders and appraisers. If you're ready to explore your options, speaking with a knowledgeable mortgage advisor at LoanWise can help you understand exactly where you stand and what steps to take next. Your home has worked hard to build equity — and with the right guidance, you can put that equity to work for you.