Inheriting a share of a home can be both a gift and a challenge. Whether you've received a portion of a property through a family estate or a relative's will, converting that partial ownership into full control — or financing it through a mortgage — involves a specific set of steps. Understanding the requirements for conventional loan with inherited partial ownership of property is essential before you approach a lender. This article walks you through the most important considerations, from title and equity rules to credit standards and co-owner agreements, so you can move forward with confidence.
What Inherited Partial Ownership Actually Means for Mortgage Purposes
When a property is passed down through an estate and multiple heirs receive ownership shares, the result is called tenancy in common or joint ownership. Each heir holds a percentage of the title, but no single person controls the entire property. This arrangement creates unique complications when one heir wants to secure conventional financing on that home.
Lenders who offer conventional loans — those backed by Fannie Mae or Freddie Mac guidelines — typically require that the borrower have a clear, insurable interest in the property. Partial ownership doesn't automatically disqualify you, but it does require careful documentation and, in many cases, the resolution of shared title before a loan can close.
It's also worth noting that inherited property is treated differently from a standard purchase in the eyes of lenders. Since no money changed hands in a traditional sale, the property's value for loan purposes is usually established through a formal appraisal rather than a purchase price. This distinction shapes how the loan-to-value ratio is calculated and how much equity you may be able to access.
Title Clarity and Co-Owner Consent: The Foundation of Your Loan
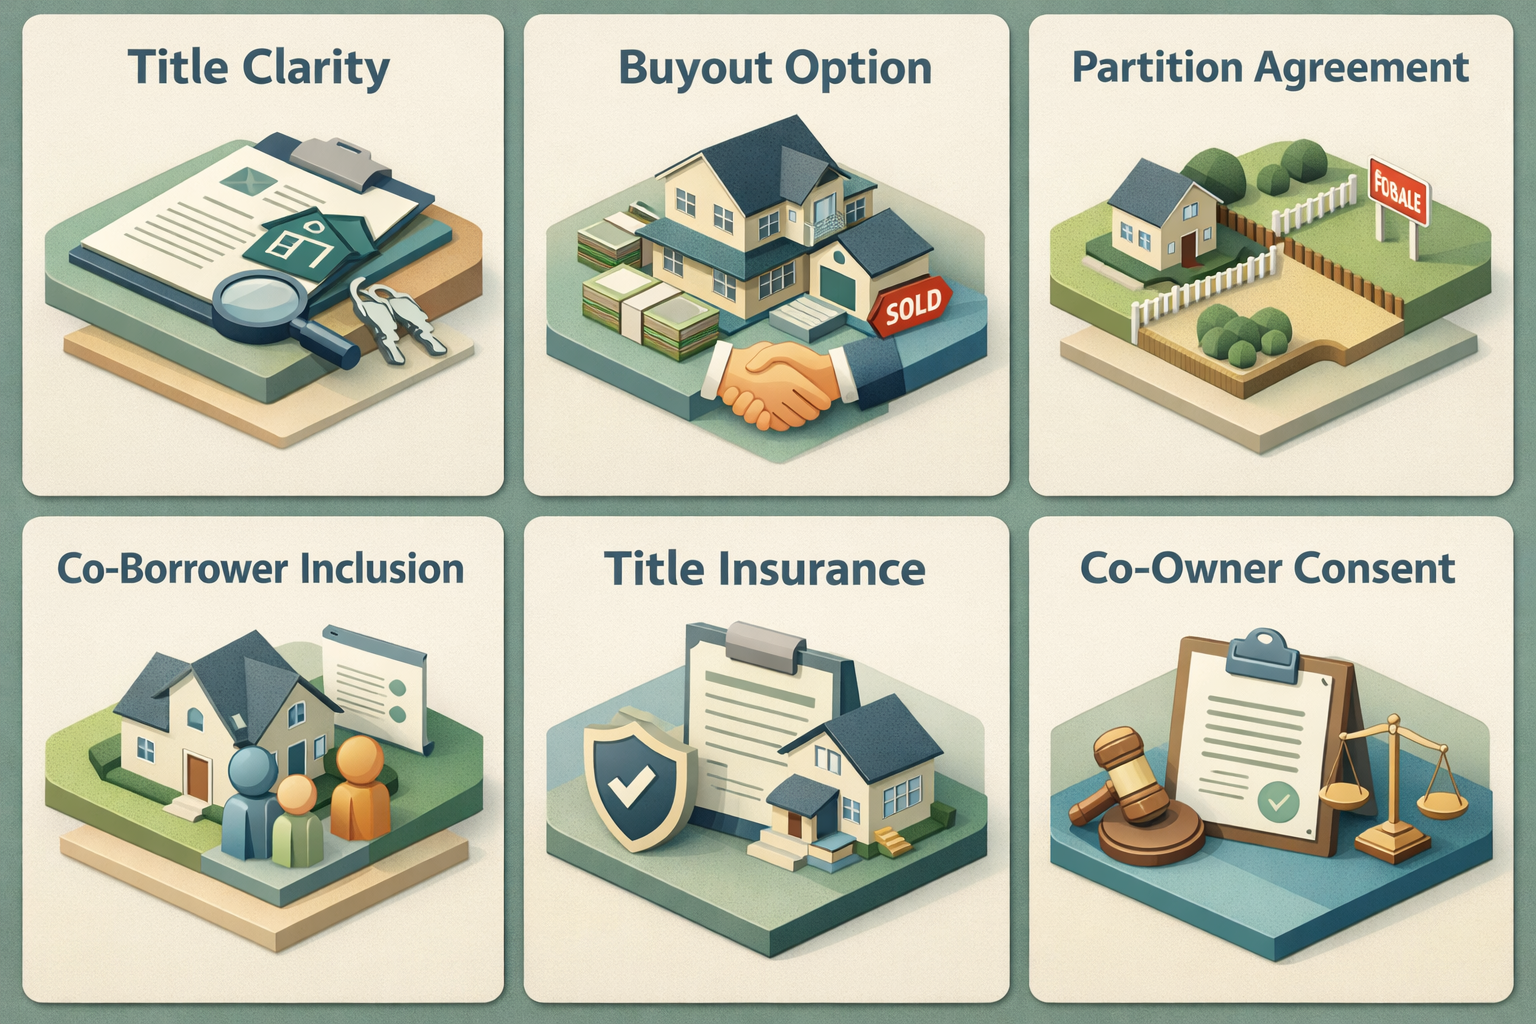
One of the most significant hurdles in meeting the requirements for conventional loan with inherited partial ownership of property is establishing a clean, lendable title. Conventional lenders require that the borrower have unencumbered ownership — or a clear path to it — before they'll approve financing. If multiple heirs still share ownership, the lender may require one of the following:
- A buyout of other co-owners: The borrower uses loan proceeds or personal funds to purchase the other heirs' shares, resulting in sole ownership before or at closing.
- A partition agreement: All co-owners legally agree to divide or sell the property, with the borrower receiving a defined share that can then be financed independently.
- Co-borrower inclusion: In some cases, all co-owners may be added to the mortgage as co-borrowers, though this approach comes with its own qualification requirements.
Title insurance plays a critical role here as well. Since inherited properties sometimes carry unresolved liens, unpaid estate taxes, or competing claims, lenders will typically require a full title search and may insist on clearing any clouds on title before proceeding. Working with a real estate attorney during this phase is strongly advisable.
Co-owner consent isn't just a courtesy — it's often a legal necessity. If other heirs don't agree to the financing arrangement or the buyout terms, the process can stall significantly. Starting family conversations early and, where needed, involving a mediator or estate attorney can help prevent costly delays.
Credit Score and Debt-to-Income Standards You'll Need to Meet
Even when the title situation is resolved, you still need to satisfy the standard borrower qualification criteria that apply to any conventional mortgage. These requirements don't change simply because the property was inherited — lenders still evaluate your financial profile with the same level of scrutiny.
For most conventional loans, a minimum credit score of 620 is typically required, though borrowers with scores in the higher ranges — generally 740 and above — tend to qualify for the most competitive interest rates. If your score falls below that threshold, it may be worth spending time improving your credit before applying.
Your debt-to-income ratio (DTI) is equally important. Conventional guidelines generally prefer a DTI at or below 43%, though some automated underwriting systems may allow slightly higher ratios depending on compensating factors like strong reserves or a larger down payment. When calculating your DTI, lenders will include the projected mortgage payment on the inherited property alongside all existing monthly debt obligations.
If you're planning to buy out other heirs using loan proceeds, the lender will also consider whether that buyout amount is being funded through the mortgage itself. This could affect your loan amount, your equity position, and the overall structure of the financing.
How Equity and Appraisal Values Affect Your Loan Options
Because inherited properties don't come with a purchase price, the appraised value becomes the anchor for all loan calculations. The loan-to-value ratio (LTV) — a key metric for conventional lenders — is determined by dividing the loan amount by the appraised value. Conventional loans typically allow LTVs up to 97% for primary residences in straightforward purchase scenarios, but inherited property situations may be treated more conservatively depending on the lender's internal guidelines.
For a partial ownership mortgage, lenders may also look at your ownership share and how it translates into equity. For example, if you inherited a 50% share of a home appraised at $400,000, your equity interest may be considered $200,000. If you're seeking to buy out the remaining 50% share, the loan structure would need to account for that transaction in a way that satisfies the lender's LTV and documentation requirements.
Some lenders may classify this type of transaction as a delayed financing or an equity buyout scenario, each of which can carry different documentation and seasoning requirements. It's important to discuss the specific loan structure with your loan officer early in the process to avoid surprises during underwriting.
Homes that need significant repairs or have deferred maintenance may also face appraisal challenges. Conventional appraisers are required to note material deficiencies, and lenders may require repairs to be completed before closing or may escrow funds to cover them.
Down Payment Requirements and Using Inherited Equity as a Source of Funds
One advantage that inheritors sometimes overlook is that existing equity in the property may reduce or eliminate the need for a traditional cash down payment. If you already own a portion of the home and are financing a buyout of the remaining shares, the equity you hold could function similarly to a down payment in the lender's calculation.
That said, credit and equity guidelines are specific about how equity from inherited property is treated. You may need to document the inheritance through probate records, a will, or a deed of distribution. The lender will want to confirm that your ownership interest is legally established and that the equity isn't being manufactured or inflated.
If a cash down payment is required in addition to your equity position, conventional loans for primary residences often start at 3% to 5% down, while investment properties typically require 15% to 25%. If the inherited home will serve as a rental or second property rather than your primary residence, expect stricter LTV limits and potentially higher interest rates.
Gift funds from family members are generally permissible under conventional guidelines for primary residences, though lenders will require a gift letter confirming that the funds don't need to be repaid. However, using gifts to fund an investment property down payment is typically not allowed under standard conventional guidelines.
Documentation Requirements That Lenders Will Expect
Meeting the requirements for conventional loan with inherited partial ownership of property involves assembling a thorough documentation package. Beyond standard loan application materials like tax returns, pay stubs, and bank statements, lenders will typically request additional paperwork specific to the inheritance situation. Here's what you should generally expect to provide:
- Probate court documents or letters testamentary confirming the estate has been administered and ownership transferred
- A copy of the will or trust document that establishes your legal right to the inherited share
- A deed of distribution or recorded deed showing your name on the title
- Signed agreements from co-heirs if a buyout or partition is occurring as part of the transaction
- A recent property appraisal from a licensed appraiser approved by the lender
- Title search results and title insurance commitment from a qualified title company
In some cases, lenders may also request a copy of the estate's final accounting or probate closing order to confirm that no outstanding claims remain against the property. The more organized and complete your documentation package, the smoother the underwriting process is likely to be.
Working with a mortgage professional who has experience in estate-related financing can be especially valuable here. They can help identify potential documentation gaps before the loan goes into underwriting, reducing the risk of delays or denials.
●Conclusion
Navigating the conventional loan inherited property process requires patience, preparation, and a clear understanding of how lenders evaluate non-traditional ownership situations. Whether you're looking to buy out your co-heirs, refinance the inherited home, or simply establish full ownership for future financing, the path forward is achievable with the right guidance. Start by resolving any title issues, gather your estate documentation, and connect with a knowledgeable loan officer who can walk you through the specific options available to you. At LoanWise, we're here to help you turn inherited opportunity into lasting financial stability — one step at a time.