Inheriting a property can feel like a financial windfall — but it also comes with a set of complex decisions, especially if you already have an existing mortgage. Whether you're hoping to keep the inherited home, sell it, rent it out, or use its equity to refinance, understanding how to calculate mortgage affordability with inherited property and existing mortgage obligations is essential. Lenders will look closely at your full financial picture, including all debts, assets, and income sources, before making a lending decision. This guide walks you through the key concepts, calculations, and strategies that could help you navigate this situation with confidence.
What Lenders Look for When You Already Have a Mortgage
When you apply for a new loan — whether it's to refinance, purchase another property, or tap into equity — lenders don't just look at your income. They assess your entire debt load relative to your earnings. This is known as your debt-to-income ratio (DTI), and it's one of the most critical factors in any mortgage qualification process.
Your DTI is calculated by dividing your total monthly debt obligations by your gross monthly income. For example, if your existing mortgage payment is $1,500 per month and your total gross monthly income is $6,000, your DTI from that single obligation is 25%. Lenders typically prefer a total DTI — meaning all debts combined — of 43% or lower, though some loan programs may allow slightly higher ratios depending on compensating factors like strong credit or significant reserves.
When an inherited property enters the picture, it can either help or complicate your DTI calculation. If the inherited home carries an outstanding mortgage that you've assumed or are now legally responsible for, that debt gets added to your monthly obligations. On the other hand, if the property is free and clear, it could represent a significant asset that strengthens your overall financial profile.
Understanding Inherited Property in the Context of Mortgage Affordability
Not all inherited properties are treated the same way by lenders. How the home is classified — primary residence, second home, or investment property — will influence how lenders count it in your financial assessment. Here are a few common scenarios:
- Inherited property with no mortgage: If the home was inherited free and clear, it may be counted as an asset. Its appraised value could strengthen your net worth, and if you plan to sell it, the proceeds might be usable as a down payment or to pay down existing debt.
- Inherited property with an assumed mortgage: If you've formally assumed the existing loan on the inherited property, that monthly payment will be included in your DTI calculation, which could reduce what you qualify for on a new loan.
- Inherited property generating rental income: If you're renting out the inherited home, lenders may allow a portion of that rental income — often around 75% of gross rent — to offset the property's expenses and reduce your effective DTI. However, most lenders will want to see documentation such as a lease agreement and potentially a history of rental income on your tax returns.
Understanding which category your inherited property falls into is the first step in figuring out how it will affect your mortgage affordability inherited property calculation.
How to Calculate Mortgage Affordability With Inherited Property and Existing Mortgage Step by Step
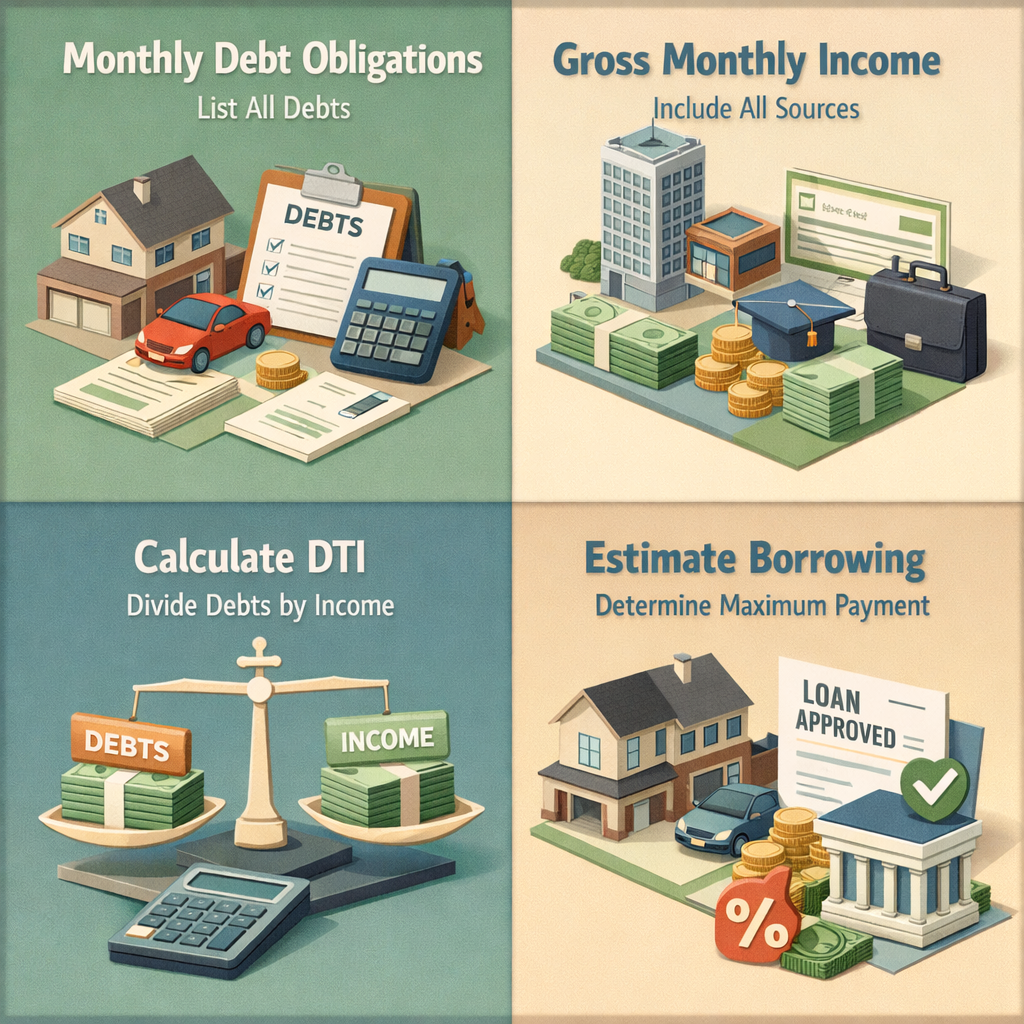
Learning how to calculate mortgage affordability with inherited property and existing mortgage balances doesn't have to be overwhelming. Breaking it down into clear steps can make the process much more manageable.
Step 1 — Add Up All Monthly Debt Obligations
Start by listing every monthly debt payment you're responsible for. This typically includes:
- Your existing mortgage payment (principal, interest, taxes, and insurance)
- Any mortgage payment on the inherited property if you've assumed it
- Car loans, student loans, and credit card minimum payments
- Any other installment loans or personal loans
Add these together to get your total monthly debt figure.
Step 2 — Calculate Your Gross Monthly Income
Next, determine your gross monthly income — this is your income before taxes and deductions. Include all qualifying income sources such as wages, self-employment income, rental income (typically at 75% of gross rent), alimony, or other documented recurring income. If the inherited property is rented out, confirm with your lender how much of that rental income they'll count.
Step 3 — Divide Debts by Income to Get Your DTI
Divide your total monthly debts by your gross monthly income and multiply by 100 to express the result as a percentage. For example:
- Total monthly debts: $2,800
- Gross monthly income: $7,000
- DTI: ($2,800 ÷ $7,000) × 100 = 40%
A DTI of 40% may still be within acceptable range for many conventional loan programs, though lenders will evaluate other factors alongside this number.
Step 4 — Estimate What You Can Borrow
Once you know your DTI, you can work backward to estimate the maximum monthly payment you can afford on a new loan. Subtract your existing monthly debts from the maximum allowable debt amount (based on the lender's DTI threshold) to find what's left for a new mortgage payment. From there, you can estimate the loan amount using a mortgage calculator with your anticipated interest rate and loan term.
How Inherited Property Equity May Help Your Loan Application
One often-overlooked advantage of inheriting a property is the equity it may bring. If the inherited home has substantial value — especially if it's mortgage-free — that equity could be leveraged in several useful ways:
- As a down payment source: Selling the inherited property could free up funds that you use toward a down payment on a new home, potentially reducing the size of your new mortgage and improving your affordability ratios.
- Cash-out refinancing: If you decide to keep the inherited property, you might consider a cash-out refinance on it to access equity while retaining ownership. That cash could then be applied to reduce your existing mortgage balance or cover other financial needs.
- Improving your net worth profile: A lender may view a borrower with significant real estate equity more favorably, as it suggests lower financial risk even if the DTI is on the higher end.
It's worth speaking with a mortgage professional to understand exactly how lenders in your area treat inherited property equity, as guidelines can vary between loan programs and individual lenders.
Calculating DTI With an Existing Mortgage and Rental Income From Inherited Property
One of the more nuanced aspects of calculating DTI with existing mortgage obligations is accounting for rental income from an inherited property correctly. Lenders don't simply add 100% of the rent you collect to your income. Instead, most lenders apply a vacancy and expense factor — commonly 25% — which means only about 75% of your gross rental income is counted toward qualifying income.
Here's a simplified example of how this might work:
- Gross monthly rent from inherited property: $1,200
- Qualifying rental income (75%): $900
- Existing mortgage payment on primary home: $1,600
- Inherited property mortgage payment (if applicable): $0 (free and clear)
- Other monthly debts: $500
- Total monthly debts: $2,100
- Gross monthly employment income: $6,500
- Total qualifying income: $6,500 + $900 = $7,400
- DTI: ($2,100 ÷ $7,400) × 100 ≈ 28.4%
In this scenario, the rental income from the inherited property actually improves affordability by boosting total qualifying income. However, if the inherited property still carries a mortgage, that payment must also be factored into the debt side of the equation, which could push the DTI higher.
Keep in mind that lenders may require documented proof of rental income, such as a current signed lease and bank statements showing deposits, before they'll count it toward qualification.
Common Challenges and How to Address Them
Navigating mortgage affordability with an inherited property can present some unique hurdles. Here are a few challenges borrowers often encounter — and practical ways to address them:
High DTI Due to Multiple Properties
Carrying an existing mortgage alongside an inherited property with an assumed loan can quickly push your DTI beyond what lenders prefer. In this case, consider whether selling one property or paying down high-interest debts could bring your ratio back into range. Refinancing your existing mortgage to a lower payment — if rates allow — might also help.
Unclear Title or Estate Issues
Inherited properties can sometimes come with title complications, especially if the estate hasn't been fully settled or if multiple heirs are involved. Lenders will generally require a clear title before they'll lend against an inherited property. Working with a real estate attorney to resolve any probate or title issues early on can prevent delays.
Insufficient Documentation of Rental Income
If you've recently started renting out the inherited property, you may not yet have a full tax year of rental income to show lenders. Some lenders may accept a signed lease as documentation, but others might require at least one or two years of tax returns showing Schedule E rental income. Being proactive about keeping thorough records from day one can make a meaningful difference.
Property Condition Affecting Appraisal Value
Inherited homes sometimes require repairs or updates, which could affect their appraised value. If you're planning to leverage the inherited property's equity, investing in key improvements before an appraisal might increase its value and, in turn, your borrowing power.
Tips for Strengthening Your Mortgage Application in This Scenario
Whether you're refinancing, purchasing a new home, or trying to access equity, there are several steps that may help improve your chances of approval when managing inherited property alongside an existing mortgage:
- Work with a knowledgeable lender: Not all lenders handle inherited property situations the same way. Seeking out a lender who has experience with these scenarios could make the process smoother and help you find the most favorable loan terms.
- Improve your credit score before applying: A higher credit score may allow you to qualify for better rates and could give lenders more flexibility on DTI limits. Paying down credit card balances and avoiding new credit applications in the months before you apply are both commonly recommended strategies.
- Reduce existing debts: Paying off smaller debts before applying could meaningfully lower your DTI, potentially making a significant difference in what you qualify for.
- Gather all documentation early: Lenders will likely request proof of the inheritance (such as a will, probate documentation, or deed transfer), along with the property's current mortgage statement if applicable, a recent appraisal or property value estimate, and any lease agreements for rental income.
- Consider a financial advisor: In complex situations involving inheritance, existing debt, and new borrowing goals, a financial advisor who understands real estate and lending can help you map out the most efficient path forward.
●Conclusion
Understanding how to calculate mortgage affordability with inherited property and existing mortgage commitments requires looking at the full picture — your debts, your income, your assets, and the specific nature of the inherited property. While the process can feel complex, breaking it down into clear steps — starting with your DTI calculation — gives you a strong foundation for making informed decisions. Whether the inherited home helps boost your income through rent, provides equity to strengthen your financial position, or creates additional debt obligations, each factor plays a role in how lenders will assess your application. At LoanWise, we're here to help you work through the numbers and explore your options. Reach out to a lending specialist today to get personalized guidance on your unique situation.