Navigating a mortgage refinance can feel overwhelming on its own. But when you add employer-provided income like a relocation bonus or stock options into the mix, the process gets even more complex. Many homeowners and relocating professionals don't realize that these income sources can actually work in their favor when exploring the best options for refinancing ARM mortgage with relocation bonus and stock options. Whether your adjustable-rate mortgage is approaching its reset period or you simply want more payment stability, understanding how lenders view non-traditional income could open doors to better loan terms, lower rates, and long-term financial confidence.
Understanding Adjustable-Rate Mortgages and Why Refinancing May Make Sense
An adjustable-rate mortgage, commonly known as an ARM, starts with a fixed interest rate for an initial period — often five, seven, or ten years. After that period ends, the rate adjusts periodically based on a market index, which means your monthly payment could go up or down depending on economic conditions.
For many homeowners, this unpredictability becomes a concern, especially when interest rates are trending upward or when long-term financial planning becomes a priority. Refinancing into a fixed-rate mortgage can offer payment stability, predictability, and sometimes a lower overall interest cost depending on current market rates and your financial profile.
There are several scenarios where refinancing your ARM might make strategic sense:
- Your initial fixed period is ending soon and you want to lock in a rate before adjustments begin.
- You've improved your credit profile significantly since taking out the original loan.
- You plan to stay in your home long-term and want the consistency of a fixed payment.
- You've recently received a salary increase, relocation package, or equity-based compensation that strengthens your financial position.
Understanding your ARM's adjustment caps, margin, and index is also important before committing to a refinance. Speaking with a licensed mortgage professional can help you calculate whether the timing is right based on your specific loan terms.
How Lenders View Relocation Bonuses as Qualifying Income
A relocation bonus is typically a lump-sum payment provided by an employer to help an employee cover the costs of moving to a new location. While this might seem straightforward, lenders tend to scrutinize relocation bonuses carefully because they're generally considered non-recurring income.
Most conventional mortgage guidelines require income to be stable and likely to continue for at least two to three years. A one-time relocation payment typically doesn't meet that threshold on its own. However, a relocation bonus may still help your refinance application in several important ways:
- Down payment or closing cost reserves: Even if a relocation bonus can't be counted as monthly qualifying income, it could strengthen your application by demonstrating cash reserves or covering out-of-pocket refinancing costs.
- Debt payoff: Using relocation funds to pay down existing debts before applying may improve your debt-to-income (DTI) ratio, which lenders use to assess repayment capacity.
- Recurring relocation assistance: In some cases where relocation allowances are paid on an ongoing or annual basis through an employer, a lender might consider a portion of that income if it's well-documented and verifiable.
Documentation is critical. Lenders will likely want to see an offer letter, employer verification, and bank statements showing the deposit. Being transparent with your mortgage professional about the source and nature of these funds from the start can help avoid delays in the underwriting process.
Using Stock Options and Equity Compensation to Strengthen Your Refinance Application
Stock options, restricted stock units (RSUs), and other forms of equity-based compensation have become increasingly common, particularly for employees at technology companies, startups, and publicly traded corporations. But how do mortgage lenders treat this type of income during a refinance?
The short answer is: it depends on the type of equity compensation and how consistently it's been received. Here's a general breakdown of how different stock-based income types are typically evaluated:
- Vested RSUs sold as cash: If you've received and sold RSUs over the past two years, lenders may average that income and count it toward your qualifying income — provided it's documented on tax returns and pay stubs.
- Stock options exercised: Similar to RSUs, exercised stock options that appear as documented income over a two-year history could be considered. Lenders often want to see consistency and may require proof that vesting will continue.
- Unvested stock options: These are generally not counted as qualifying income since they haven't been realized. However, they may still be listed as an asset in some loan scenarios.
- Employee Stock Purchase Plans (ESPP): Income from ESPP shares sold may be usable if it appears consistently on tax returns, though this varies by lender and loan program.
Because equity compensation varies so widely by employer, industry, and vesting schedule, it's important to work with a lender experienced in non-traditional income documentation. Non-QM (non-qualified mortgage) loan programs may offer more flexibility in how this income is assessed compared to conventional loan guidelines.
Best Options for Refinancing ARM Mortgage with Relocation Bonus and Stock Options
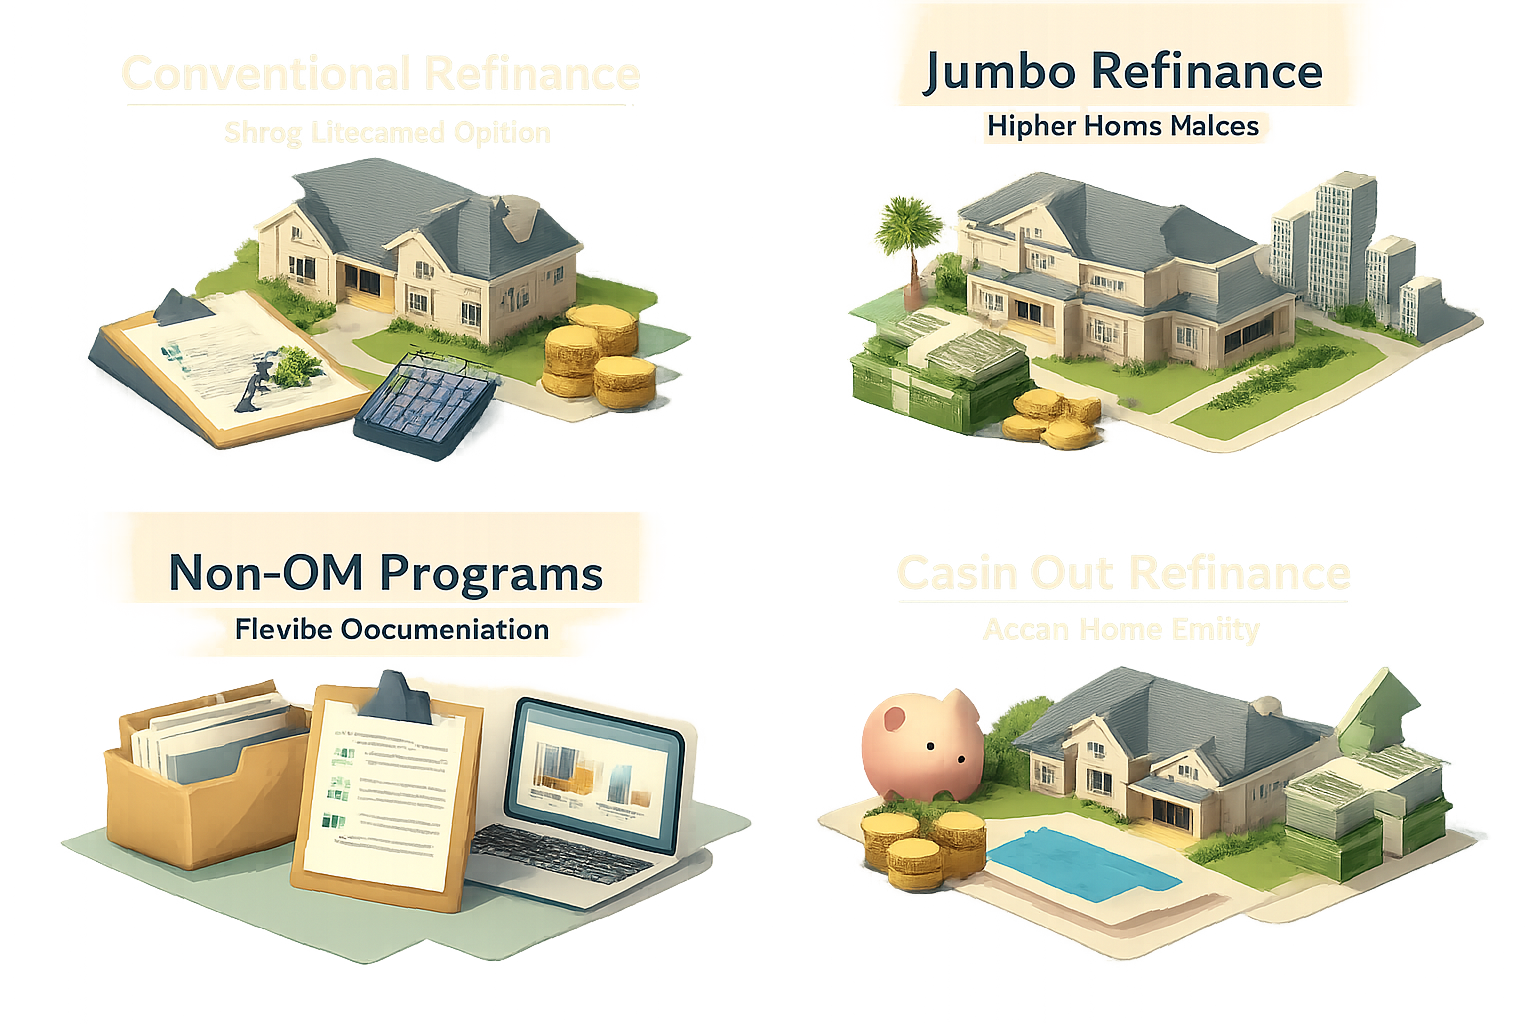
If you're actively exploring the best options for refinancing ARM mortgage with relocation bonus and stock options, you'll want to match your income profile to the right loan program. Here are the most relevant refinance pathways worth considering:
Conventional Rate-and-Term Refinance
This is the most straightforward option for borrowers with strong credit and documented income. If your stock option income has a two-year history on tax returns, a conventional refinance with Fannie Mae or Freddie Mac guidelines may allow that income to be averaged and counted toward your DTI. This path typically offers competitive interest rates and no mortgage insurance requirement if your equity is above 20 percent.
Jumbo Refinance Loans
Tech professionals and executives receiving stock-based compensation often have higher home values that exceed conforming loan limits. Jumbo refinance programs typically allow more flexibility in how alternative income types are documented, though underwriting standards can be more rigorous. A strong asset base combined with vested equity income may make jumbo refinancing accessible even with a non-traditional income profile.
Non-QM Refinance Programs
Non-qualified mortgage programs are specifically designed for borrowers who don't fit traditional income boxes. If your relocation bonus or stock compensation doesn't meet standard documentation requirements, a non-QM lender may accept bank statements, asset depletion strategies, or letter-of-explanation documentation in lieu of standard pay stubs and W-2s. These loans may come with slightly higher rates, but they offer an important pathway for income-complex borrowers.
Cash-Out Refinance
If you've built equity in your home, a cash-out refinance allows you to tap that equity while also switching from your ARM to a fixed-rate product. Some homeowners in this situation use the cash-out proceeds alongside a relocation bonus to restructure debt, improve reserves, or fund major expenses — which may ultimately improve their overall financial picture.
Debt-to-Income Ratio Strategies When Income Is Variable
Your debt-to-income (DTI) ratio is one of the most important numbers in any mortgage application. Most conventional lenders prefer a DTI at or below 43 to 45 percent, though some programs may allow higher ratios with compensating factors like strong credit or significant reserves.
When your income includes variable elements like bonuses or stock distributions, managing your DTI strategically becomes especially important. Here are some approaches that may help:
- Pay down installment debt: Using your relocation bonus to pay off a car loan or student loan balance could meaningfully reduce your monthly debt obligations before your refinance application is submitted.
- Avoid taking on new debt: New credit inquiries or additional loan obligations close to your refinance timeline can raise your DTI and lower your credit score temporarily.
- Document all income streams thoroughly: Lenders appreciate clear, organized documentation. Two years of tax returns, W-2s, brokerage statements, and employer letters that explain vesting schedules all contribute to a cleaner underwriting process.
- Build strong reserves: Even if a relocation bonus doesn't count as qualifying income, showing that you have several months of mortgage payments in reserve can be a powerful compensating factor for lenders.
Working closely with a mortgage advisor who understands both conventional and non-QM guidelines gives you the best chance of structuring your application in a way that reflects your true financial strength.
Timing Your Refinance Around Equity Compensation Events
One often-overlooked aspect of ARM refinance strategy is the timing of your application relative to equity compensation events. Vesting dates, exercise windows, and year-end bonus distributions can all affect how your income appears on paper — and that affects what lenders see when they evaluate your file.
Here are some timing considerations worth discussing with your mortgage professional:
- Apply after two years of consistent equity income: If you recently started a job with stock benefits, waiting until you have two years of documented income history on tax returns may significantly improve your qualifying income picture.
- Time your application after a large RSU vesting event: Receiving and selling RSUs close to your refinance date could demonstrate strong liquid reserves and recent income that supports your application.
- Consider the rate environment: Refinancing only makes financial sense if the new rate is meaningfully lower than what you'd pay on your adjusted ARM rate. Running a break-even analysis with a mortgage calculator helps determine if the savings justify the closing costs.
- Factor in relocation timing: If you recently relocated and are settling into a new home or community, confirming your long-term intent to stay in the property may be important for lender confidence, especially with cash-out refinance products.
Strategic timing isn't about gaming the system — it's about presenting a mortgage application at the moment when your financial profile is strongest and most clearly documented.
Working with the Right Lender for a Complex Income Profile
Not every lender has experience handling the nuances of equity-based compensation or employer relocation packages. Choosing a mortgage professional who is familiar with these income types could be the difference between a smooth closing and a frustrating denial.
Here's what to look for when selecting a lender for this type of refinance:
- Experience with non-traditional income: Ask directly whether the lender has worked with borrowers who receive RSUs, stock options, or employer relocation packages. Request examples or ask how these income types are typically treated in underwriting.
- Access to multiple loan programs: A mortgage broker or lender with access to both conventional and non-QM products gives you more flexibility than one who only offers standard agency loans.
- Transparent communication: A good lender will review your income documentation upfront, identify any gaps, and give you a realistic picture of what programs you qualify for before you commit to an application.
- Strong pre-approval process: Look for lenders who offer a thorough pre-approval rather than a simple pre-qualification. For complex income profiles, detailed upfront underwriting reduces the risk of surprises later in the process.
At LoanWise, our team understands that today's borrowers often have multi-layered income profiles. Whether you're leveraging ARM refinance relocation bonus stock options income or navigating equity compensation for the first time, we're here to help you find a refinance strategy that fits your life and your goals.
●Conclusion
Refinancing an ARM mortgage when you have a relocation bonus or stock options in the picture requires thoughtful planning, the right documentation, and a lender who truly understands your financial profile. The best options for refinancing ARM mortgage with relocation bonus and stock options will vary based on your loan amount, income history, credit profile, and how your employer structures your compensation. What matters most is approaching the process proactively — documenting your income clearly, managing your DTI strategically, and timing your application when your financial picture is at its strongest. If you're ready to explore your refinance options, connect with a LoanWise mortgage expert today and let's find the path that works best for you.