Starting a mobile pet grooming business is an exciting venture. Pet ownership continues to grow across the United States, and demand for convenient, at-home grooming services is stronger than ever. If you're an entrepreneur ready to hit the road with clippers and shampoo, securing the right funding is one of your most important first steps. An SBA loan could be the ideal financing solution — offering competitive rates, flexible terms, and access to capital that many new small businesses simply can't get elsewhere. But before a lender can say yes, you'll need to come prepared. Understanding exactly what documents needed for SBA loan for a new mobile pet grooming business is the key to moving your application forward with confidence. This guide walks you through every piece of paperwork, explains why each one matters, and offers practical tips to help you get organized before you ever walk through a lender's door.
Why an SBA Loan Makes Sense for a Mobile Pet Grooming Startup
SBA loans are partially guaranteed by the U.S. Small Business Administration, which reduces the risk for participating lenders and opens doors for borrowers who may not yet have an established business history. For an SBA loan mobile pet grooming startup, this type of financing can cover a wide range of startup costs — from purchasing a fully equipped grooming van to buying professional tools, insurance, and initial marketing materials.
The most commonly used SBA loan program for startups is the SBA 7(a) loan, which may provide up to $5 million in financing depending on your qualifications. For smaller capital needs, the SBA Microloan program could be a better fit, offering loans typically up to $50,000 through nonprofit intermediary lenders. Both programs are worth exploring depending on your projected startup budget.
Because you're launching a brand-new business, lenders will rely heavily on your personal financial strength, your business plan, and your ability to demonstrate that you understand the market. That's exactly why having your documents ready and well-organized can make a meaningful difference in how quickly — and successfully — your application moves forward.
Personal Financial Documents Every Applicant Needs
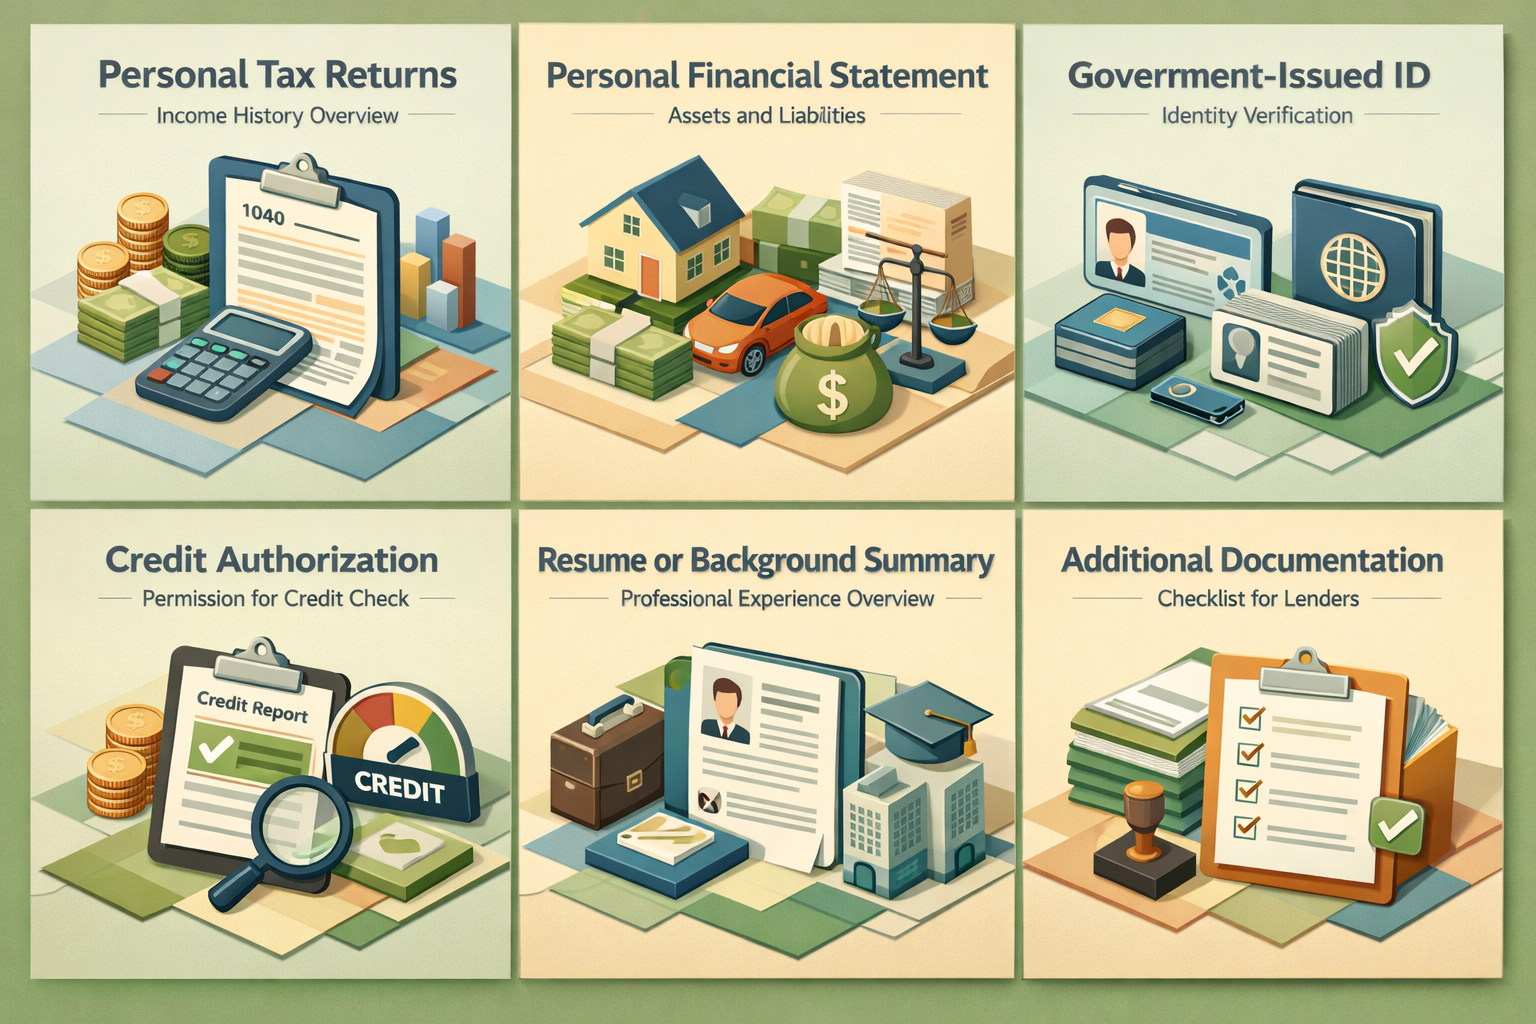
Since your mobile pet grooming business is new, lenders will look closely at your personal finances to evaluate creditworthiness. The following personal documents are typically required for any SBA loan application:
- Personal tax returns: Most lenders request the last two to three years of personal federal tax returns. These give lenders a clear picture of your income history and financial habits.
- Personal financial statement: The SBA Form 413 is a standard personal financial statement that lists your assets, liabilities, and net worth. Completing this form accurately is essential.
- Government-issued ID: A valid driver's license or passport is needed to verify your identity.
- Credit authorization: Lenders will request permission to pull your personal credit report. A strong credit score — generally 650 or higher — may improve your chances of approval, though requirements can vary by lender.
- Resume or background summary: Because this is a new business, lenders may want to see your professional background and any relevant experience in pet grooming, animal care, or small business management.
It's worth noting that some SBA lenders may have additional personal documentation requirements, so it's always a good idea to ask your lender for a complete checklist early in the process.
Business Plan Requirements That Lenders Carefully Review
For a startup like a mobile pet grooming business, your business plan may be the single most important document in your application. Since there's no operating history to review, lenders depend on your business plan to assess whether your venture is viable and whether you have a realistic strategy for generating revenue and repaying the loan.
A strong SBA loan business plan for a mobile pet grooming startup should include:
- Executive summary: A concise overview of your business concept, target market, and funding request.
- Company description: Details about your business structure, the services you'll offer, and your service area or territory.
- Market analysis: Research on the local demand for pet grooming, your target customer base, competitor landscape, and pricing strategy.
- Operations plan: How you'll run the business day to day — including your grooming van, equipment, scheduling process, and any staff you plan to hire.
- Marketing and sales strategy: How you'll attract and retain clients, whether through social media, referrals, local advertising, or partnerships with veterinary offices.
- Financial projections: Month-by-month revenue and expense forecasts for at least the first two to three years, along with a break-even analysis.
- Funding request: A clear explanation of how much you're requesting, what it will be used for, and how you plan to repay it.
Lenders want to see that you've done your homework and that your projections are grounded in realistic assumptions. Overly optimistic numbers without supporting data can raise red flags during underwriting.
What Documents Needed for SBA Loan for a New Mobile Pet Grooming Business: Entity and Legal Paperwork
Beyond your personal finances and business plan, lenders will also want to verify that your business is properly established as a legal entity. These documents confirm that your mobile pet grooming business is organized, compliant, and ready to operate. Common requirements include:
- Business formation documents: Articles of incorporation, articles of organization (for LLCs), or a DBA (doing business as) filing — depending on how your business is structured.
- Employer Identification Number (EIN): This is your business tax ID issued by the IRS. You can apply for one online at no cost.
- Business licenses and permits: Depending on your state and city, you may need a general business license, a professional grooming certification, or a mobile business permit. Some municipalities also have specific regulations for vehicle-based service businesses.
- Operating agreement or bylaws: If your business has partners or multiple owners, lenders may require your LLC operating agreement or corporate bylaws to understand ownership structure.
- Ownership and affiliate information: The SBA requires disclosure of all owners holding 20% or more of the business, along with any affiliated businesses they may own.
If you haven't formally registered your business yet, it's generally a good idea to do so before applying for financing. Operating as a legally registered entity tends to strengthen your credibility with lenders and may be required to proceed with the application.
Financial Projections and Startup Cost Documentation
Because your mobile pet grooming business is new, you won't have historical financial statements to submit. Instead, lenders will ask for forward-looking financial documents that demonstrate your understanding of startup costs and expected revenue. Prepare to provide:
- Startup cost breakdown: A detailed list of all expenses needed to launch — including your grooming van or trailer, grooming equipment, product inventory, insurance, branding, website development, and licensing fees.
- Projected profit and loss statement: Month-by-month income and expense projections, typically covering 24 to 36 months.
- Projected cash flow statement: A forecast showing when money is expected to come in and go out, which helps lenders assess your ability to make loan payments.
- Projected balance sheet: A snapshot of what your business assets, liabilities, and equity will look like at the end of your first year.
- Use of funds statement: A clear breakdown of exactly how the loan proceeds will be spent.
Your financial projections should be realistic and supported by market research wherever possible. If you're quoting vendor prices for equipment or vehicles, consider attaching supporting quotes or estimates to your application. This level of detail can demonstrate thoroughness and build lender confidence.
Collateral, Insurance, and Other Supporting Documents
SBA loans often require collateral to secure the financing, particularly for larger loan amounts. For a mobile pet grooming business, your grooming van itself may serve as collateral, along with personal assets if the loan amount requires it. Here's what you might need in this category:
- Collateral documentation: If you're purchasing a vehicle or equipment with the loan, lenders may ask for purchase agreements or invoices. If personal assets are involved, you may need property records or account statements.
- Business insurance: Lenders typically require proof of general liability insurance. For a mobile grooming business, you may also need commercial auto insurance for your van. Some lenders may require that the lender be listed as an additional insured on certain policies.
- Franchise agreement (if applicable): If you're buying into a mobile pet grooming franchise, lenders will want to review the franchise disclosure document and your franchise agreement.
- Signed purchase agreements or letters of intent: If you've already identified a van or equipment to purchase, having a signed agreement or letter of intent from the seller can strengthen your application.
It's also common for SBA lenders to request a signed SBA borrower information form (SBA Form 1919) as part of the formal application package. This form collects background information on the business and all owners. Make sure to complete it fully and honestly, as any discrepancies could slow down or jeopardize your approval.
Tips to Organize and Submit a Stronger Loan Application
Gathering all the right documents is only half the battle. How you present them can also influence how quickly your application is reviewed and how favorably lenders respond. Here are some practical strategies to help you submit a polished, complete package:
- Create a document checklist: Use a master checklist to track every required item. Check off each document as you gather it and make note of anything still outstanding.
- Organize documents logically: Group documents by category — personal financials, business plan, legal formation, financial projections, and collateral. Label each section clearly.
- Review for accuracy: Double-check that all names, dates, and figures are consistent across documents. Inconsistencies between your tax returns and financial statements, for example, can raise questions.
- Work with an SBA-approved lender early: Connecting with an experienced SBA lender before you finalize your documents can save you time. They can tell you exactly what their institution requires and flag any gaps in your package.
- Consider working with a SCORE mentor or SBDC advisor: The Small Business Development Center (SBDC) and SCORE offer free guidance to entrepreneurs. Their advisors can help you refine your business plan and financial projections before you submit.
- Keep digital and physical copies: Store all documents in both formats. Cloud storage can make sharing with lenders easier, while physical copies are helpful for in-person meetings.
Starting organized sets a professional tone from the very first interaction and signals to lenders that you're serious, prepared, and capable of managing a business responsibly.
●Conclusion
Launching a mobile pet grooming business is a rewarding path for entrepreneurs who love animals and value independence. And with the right financing in place, you can hit the road with confidence. Understanding what documents needed for SBA loan for a new mobile pet grooming business is your first step toward a successful application. From personal tax returns and a detailed business plan to legal formation documents and startup cost projections, each piece of paperwork plays a role in helping lenders evaluate your readiness and your vision. The more complete and well-organized your application, the smoother the review process tends to go. At LoanWise, we're here to help small business owners and entrepreneurs navigate the lending landscape with clarity. If you're ready to explore your SBA loan options for your SBA loan mobile pet grooming startup, connect with a lending specialist today and take the next step toward turning your business dream into a moving reality.