Starting a mobile car wash business is an exciting venture for entrepreneurs who want low overhead costs and flexible operations. But like any new business, it needs funding — and that's where an SBA loan for car wash startups can make a real difference. The U.S. Small Business Administration (SBA) backs several loan programs designed to help new businesses get off the ground, even when traditional lenders might be hesitant. The challenge for many first-time borrowers, though, is understanding exactly what documents are needed for an SBA loan for a new mobile car wash startup. Getting this right from the start could be the difference between a smooth approval and a frustrating delay. This guide walks you through everything you'll likely need — and how to put your best foot forward with lenders.
Why SBA Loans Are a Smart Choice for a Mobile Car Wash Startup
Before diving into the paperwork, it's worth understanding why an SBA loan could be the right fit for your mobile car wash venture. Unlike conventional business loans, SBA-backed loans typically offer lower down payments, longer repayment terms, and more flexible credit requirements. These features can be especially helpful for startup loan mobile business owners who don't yet have years of revenue history to show lenders.
The most commonly used SBA programs for startups include the SBA 7(a) loan, which is the agency's flagship product for general business purposes, and the SBA Microloan program, which may be a better fit if you need a smaller amount to cover equipment like pressure washers, water tanks, and a work vehicle. The 7(a) program can fund up to $5 million, while Microloans cap out at $50,000 — a range that suits most mobile car wash startups quite well.
Because the SBA guarantees a portion of these loans, lenders take on less risk. That means they may be more willing to work with entrepreneurs who are just getting started. Still, you'll need to demonstrate creditworthiness, a viable business plan, and the ability to repay — which is where solid documentation becomes essential.
The Core Business Documents Lenders Will Ask For
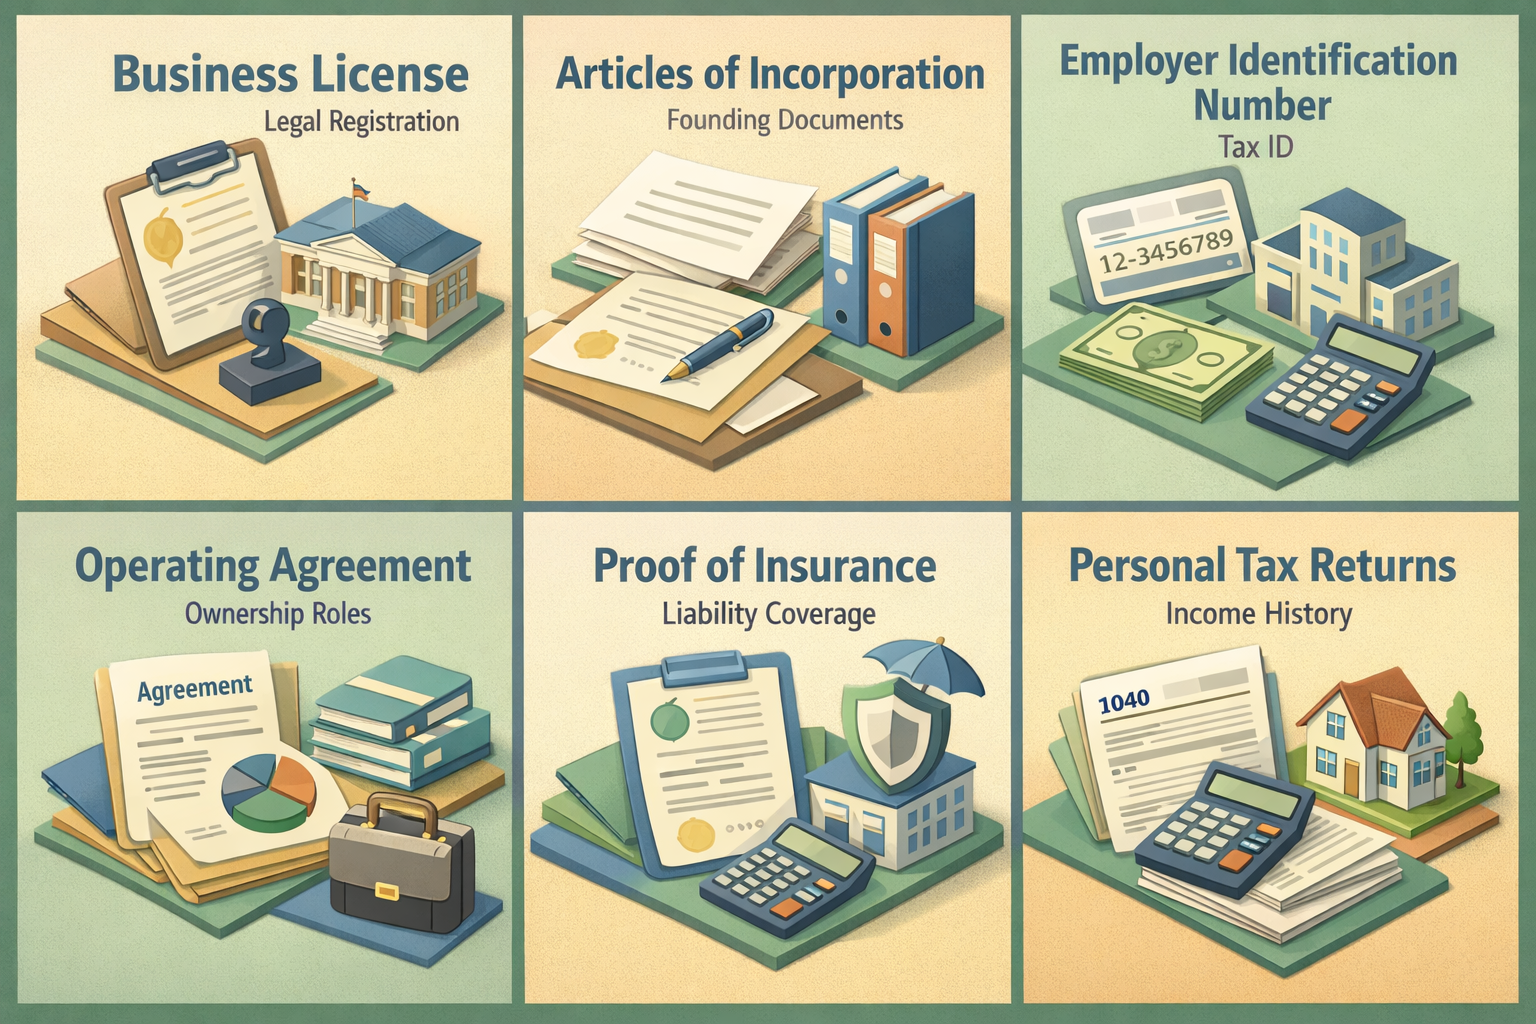
When applying for an SBA loan, lenders will want to see that your mobile car wash business is legally established and properly organized. Even as a startup, you're expected to have foundational new business documentation in place. Here's what you'll typically need:
- Business license and registration: Proof that your mobile car wash is legally registered in your state or municipality. This may include a DBA (doing business as) filing if you're operating under a trade name.
- Articles of Incorporation or Organization: If you've formed an LLC or corporation, you'll need these founding documents.
- Employer Identification Number (EIN): Issued by the IRS, this is essentially your business's tax ID and is required for most SBA applications.
- Business operating agreement or partnership agreement: If you have co-owners or partners, this document outlines each party's role and ownership percentage.
- Proof of business insurance: Lenders often require evidence that your mobile car wash has appropriate liability coverage before approving funding.
These documents establish that your business is a real, structured entity — not just an idea. Getting them in order early could speed up the review process significantly.
Personal Financial Documents Every SBA Applicant Needs
Because your mobile car wash is a new business without a lengthy financial track record, lenders will rely heavily on your personal financial profile to assess risk. This is standard practice for startup borrowers, and it's important to be prepared with the following:
- Personal tax returns: Most SBA lenders will request two to three years of personal federal tax returns. These help lenders understand your income history and financial habits.
- Personal financial statement (SBA Form 413): This form documents your personal assets, liabilities, and net worth. It's a standard SBA requirement across most loan programs.
- Personal bank statements: Lenders may ask for three to six months of recent statements to verify your liquidity and cash management behavior.
- Credit report authorization: You'll typically need to consent to a credit check. While there's no universal minimum score, a credit score in the mid-600s or higher may improve your chances with many SBA lenders.
- Resume or biography: Lenders want to know who they're lending to. A brief professional resume that highlights any relevant experience — such as customer service, auto detailing, or prior business ownership — can strengthen your application.
Keep in mind that if you have any co-owners with 20% or more stake in the business, they'll generally need to submit their own personal financial documents as well.
What Documents Are Needed for an SBA Loan for a New Mobile Car Wash Startup: The Business Plan
One of the most critical components of your SBA loan application is a well-crafted business plan. For a startup, this document essentially replaces the revenue history you don't yet have. It tells lenders where your business is going, how you plan to get there, and why you're likely to succeed. A strong business plan for a mobile car wash startup should include:
- Executive summary: A concise overview of your business concept, target market, and goals.
- Market analysis: Research on your local demand for mobile car wash services, your competition, and how you plan to stand out.
- Services and pricing: A clear breakdown of the services you'll offer — such as exterior wash, interior detailing, or fleet contracts — along with your pricing structure.
- Marketing and customer acquisition strategy: How you'll attract and retain customers, whether through social media, local advertising, partnerships with dealerships, or subscription-based service plans.
- Operational plan: Details about your equipment, service area, staffing needs, and daily workflow.
- Financial projections: Projected income statements, cash flow forecasts, and a break-even analysis for at least the first two to three years. These numbers should be realistic and supported by your market research.
Lenders use the business plan to evaluate whether your mobile car wash concept is financially viable. The more thorough and data-driven your plan, the more confidence it tends to inspire in the review process.
Equipment, Collateral, and Startup Cost Documentation
Mobile car wash businesses rely on specific equipment to operate — and SBA lenders will want to understand exactly how you plan to use the loan funds. This means providing detailed documentation around your startup costs and any assets that may serve as collateral.
You'll likely need to provide:
- Itemized use of funds statement: A clear breakdown of how the loan proceeds will be spent. For a mobile car wash, this might include purchasing a work van or truck, pressure washing equipment, water tanks, eco-friendly cleaning supplies, marketing materials, and working capital for the first few months of operation.
- Vendor quotes or purchase agreements: If you've already identified suppliers for your equipment, providing actual quotes adds credibility and precision to your cost estimates.
- Collateral documentation: SBA loans often require collateral when it's available. This could include the vehicle you plan to use for the business, personal real estate, or other business assets. If you don't have significant collateral, the SBA's guarantee may help offset this — but lenders will still document whatever assets exist.
- Franchise agreement (if applicable): If your mobile car wash operates under a franchise model, you'll need to provide a copy of the franchise disclosure document and franchise agreement.
Being specific about how you'll use the funds demonstrates financial discipline and helps lenders feel confident that you've thought through the operational side of the business.
SBA-Specific Forms and Certifications to Complete
Beyond the standard financial and business documents, SBA loan applications require several agency-specific forms. These are non-negotiable — missing even one could delay or derail your application. While the exact forms may vary slightly by lender and loan type, the most commonly required ones include:
- SBA Form 1919 – Borrower Information Form: This form collects background information about the business and its owners, including questions about legal history, citizenship, and prior government loans.
- SBA Form 413 – Personal Financial Statement: As mentioned earlier, this document is typically required for all owners with 20% or greater stake in the business.
- SBA Form 148 – Unconditional Guarantee: Owners may be required to personally guarantee the loan, meaning they accept personal liability if the business defaults.
- Statement of personal history: Lenders may request this to verify there are no disqualifying legal issues on your record.
Your lender will generally guide you through the SBA forms process, but it's smart to familiarize yourself with these documents in advance. Many SBA-approved lenders — including community banks, credit unions, and online lenders — have streamlined portals that make form submission easier for startup borrowers.
Tips to Strengthen Your SBA Loan Application as a New Entrepreneur
Knowing what documents are needed for an SBA loan for a new mobile car wash startup is only half the battle. How you present those documents matters just as much. Here are some practical strategies to improve your approval odds:
- Work with an SBA-preferred lender: These lenders have a higher approval authority and may be able to process your application faster than standard SBA lenders.
- Consult a SCORE mentor or SBDC advisor: The SBA's network of free business advisors can help you refine your business plan and review your financial projections before you apply.
- Check and improve your credit before applying: Review your personal credit report for errors and, if possible, pay down existing debt to improve your debt-to-income ratio.
- Show skin in the game: SBA lenders typically look for borrowers who are investing their own funds into the business. Having a down payment or equity injection — often around 10% to 30% of the total project cost — can make a meaningful difference.
- Be organized and complete: Submitting a neat, well-organized application package with all required documents from the start reduces back-and-forth and helps move your file forward more efficiently.
- Explain any red flags proactively: If you have a gap in employment, a prior bankruptcy, or limited credit history, address it directly in a brief written explanation. Lenders appreciate transparency.
Taking these steps before you submit could save you weeks of waiting and significantly improve the lender's overall impression of your readiness as a borrower.
●Conclusion
Launching a mobile car wash startup is a promising path for entrepreneurs who value flexibility and low overhead — and an SBA loan could be the financial foundation that makes it possible. Understanding what documents are needed for an SBA loan for a new mobile car wash startup puts you ahead of most applicants who show up unprepared. From personal financial statements and tax returns to a detailed business plan and SBA-specific forms, each document plays a specific role in helping lenders evaluate your creditworthiness and the viability of your venture. The process may feel involved, but with the right preparation, it's entirely manageable. At LoanWise, we're here to help small business owners and entrepreneurs navigate the lending landscape with confidence. Whether you're exploring an SBA loan for car wash operations or researching other startup loan mobile business options, our team can help you find the right path forward. Reach out to a LoanWise lending specialist today and take the first step toward turning your mobile car wash idea into a fully funded reality.