Refinancing an adjustable-rate mortgage can be a smart financial move — but when your income comes from 1099 contracts, overtime, or other variable sources, the process can feel a lot more complicated than it needs to be. Lenders typically want to see stable, predictable income, and variable earnings don't always fit neatly into their standard boxes. That said, homeowners in this situation have more options than they might realize. Understanding how lenders view your income, which loan programs may be most flexible, and how to present your financial profile effectively can make a real difference. This guide walks through the best options for refinancing ARM mortgage with variable 1099 overtime pay, so you can approach the process with clarity and confidence.
Why Refinancing an ARM Can Be Worth the Effort
An adjustable-rate mortgage, or ARM, typically starts with a lower introductory interest rate that adjusts periodically based on a market index. While this can be appealing at first, rate adjustments can lead to higher monthly payments over time — sometimes significantly so. For homeowners earning variable income, unpredictable mortgage payments on top of unpredictable earnings can create real financial stress.
Refinancing into a fixed-rate mortgage is often the primary goal for ARM holders looking for stability. A fixed rate locks in your monthly payment for the life of the loan, making budgeting much easier. Even if today's fixed rates are somewhat higher than your current ARM rate, the long-term predictability may well be worth the trade-off — especially if your ARM is approaching an adjustment period.
Beyond payment stability, refinancing may also offer opportunities to lower your overall interest rate if market conditions have improved since your original loan, access home equity through a cash-out refinance, or shorten your loan term. For homeowners with 1099 income or overtime pay, the key challenge isn't necessarily the goal — it's qualifying under lender guidelines that weren't always designed with non-traditional earners in mind.
How Lenders Evaluate Variable and 1099 Income During a Refinance
When you apply to refinance, lenders calculate your qualifying income to determine whether you can afford the new loan payment. For W-2 employees with salaried positions, this is straightforward. For borrowers who earn 1099 income, overtime pay, or other variable compensation, the process involves a bit more scrutiny.
Understanding How 1099 Income Is Treated
If you receive 1099 income — whether as an independent contractor, freelancer, or self-employed professional — lenders will typically look at your last two years of federal tax returns to calculate your average net income. This is important because lenders generally use your net income after business deductions, not your gross earnings. If you take significant write-offs, your qualifying income could appear lower than what you actually earn and spend day-to-day.
Some lenders may accept bank statement programs as an alternative, averaging 12 to 24 months of deposits to determine income. This approach can be more favorable for borrowers whose tax returns don't reflect their true earning capacity. However, bank statement loans often fall under non-QM (non-qualified mortgage) guidelines and may carry slightly different rate structures.
How Overtime Pay Is Calculated
Overtime income is treated as variable income by most lenders. To use it for qualifying purposes, you'll typically need to show a two-year history of receiving overtime through pay stubs, W-2s, or employer letters confirming that the overtime is likely to continue. Lenders may average your overtime over 24 months to arrive at a monthly figure. If your overtime has been inconsistent or has recently increased significantly, some lenders may discount it or exclude it entirely from your qualifying income calculation.
Loan Programs That May Work Well for Variable Income Borrowers
Not all mortgage programs treat variable income the same way. Some may be more accommodating than others depending on your specific income mix, credit profile, and loan-to-value ratio.
Conventional Loans with Fannie Mae or Freddie Mac Guidelines
Conventional loans backed by Fannie Mae or Freddie Mac do allow for the use of 1099 income and overtime, but they follow specific documentation requirements. Fannie Mae, for instance, has guidelines that allow self-employment income to be averaged over two years when it's stable or increasing. If your income has declined year-over-year, lenders may use the lower figure or decline to count that income entirely. It's worth speaking with a loan officer familiar with these guidelines to understand exactly how your income would be calculated under a conventional refinance.
FHA Refinance Options
FHA loans are government-backed mortgages that tend to have more flexible qualifying criteria. For borrowers with variable income, FHA guidelines generally follow similar two-year averaging rules, but the program's lower credit score thresholds and more lenient debt-to-income ratios may make approval more accessible. An FHA streamline refinance — which is available to existing FHA borrowers — may also offer a simplified path with reduced documentation requirements, though it typically requires a net tangible benefit to the borrower, such as a lower payment.
Non-QM and Bank Statement Loans
For borrowers whose tax returns significantly understate their income due to legitimate deductions, non-QM loan programs may be the most practical path. These loans are not required to meet standard qualified mortgage guidelines, giving lenders more flexibility in how they evaluate income. Bank statement programs, asset depletion loans, and 1099-only loans are among the options that might be available. These programs are often offered by specialty lenders and may come with slightly higher interest rates to offset the additional risk, but they can be a viable solution when traditional programs fall short.
Strategies to Strengthen Your Refinance Application
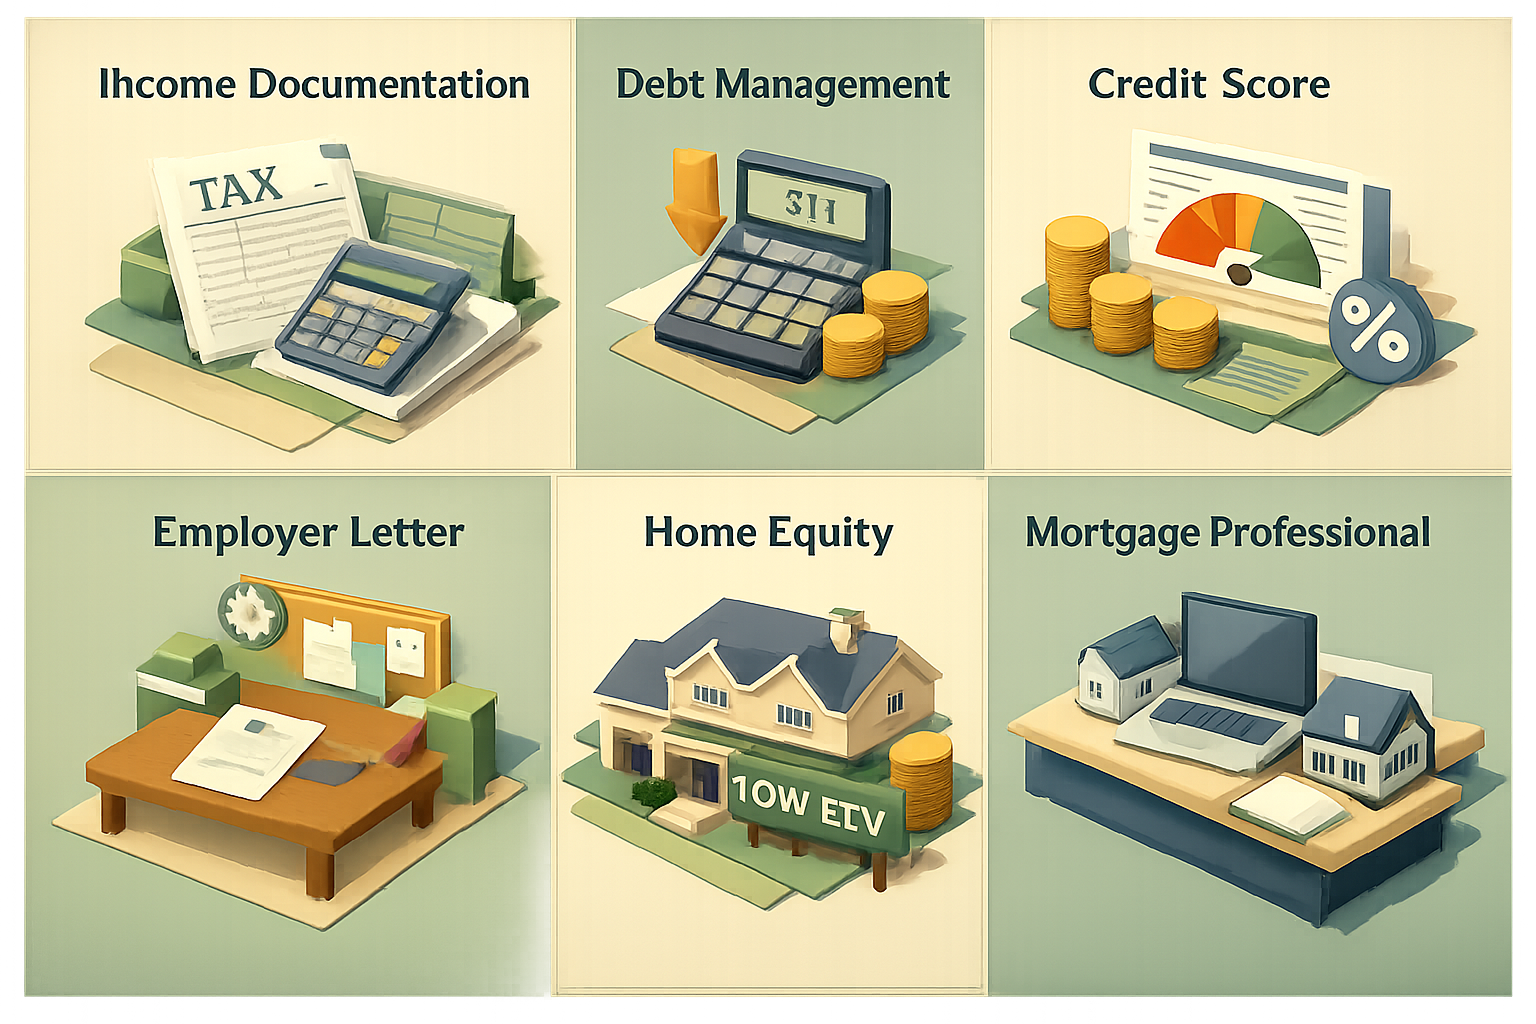
When your income is variable, how you present your financial profile matters just as much as the numbers themselves. A few strategic steps can improve your chances of approval and potentially help you qualify for better terms.
- Organize two years of tax returns: Lenders will want to see both personal and business returns if you're self-employed. Make sure they're filed and accurate before applying.
- Maintain strong bank statements: Consistent deposits that reflect your actual income can support your case, especially if you're pursuing a bank statement loan program.
- Reduce your debt-to-income ratio: Paying down credit cards or other revolving debts before applying can lower your DTI, which is a key metric lenders use to assess risk.
- Check and improve your credit score: Even a modest improvement in your credit score can open access to better rate tiers and more flexible programs.
- Get a letter from your employer or clients: For overtime income, an employer letter confirming the likelihood of continued overtime can help. For 1099 work, letters from established clients or contracts can demonstrate income continuity.
- Build up your home equity: A lower loan-to-value ratio generally gives lenders more confidence and may improve your rate or eliminate the need for mortgage insurance.
Working with a mortgage professional who has experience with variable and self-employed income can also make a meaningful difference. They can help you identify the programs most likely to work for your situation and guide you through the documentation process efficiently.
Timing Your Refinance as a Variable Income Earner
Timing a refinance involves more than just watching interest rate trends. For borrowers with 1099 or overtime income, it also means thinking about the strength of your income documentation at any given time.
If your income has been growing steadily, waiting until after you've filed a strong second year of tax returns could improve your qualifying income average. Conversely, if you had an unusually high-earning year that won't be repeated, applying sooner — while that year is still recent — might work in your favor.
Rate environment matters too. If your ARM is approaching a rate adjustment cap and the broader market suggests rates may remain elevated, locking into a fixed rate sooner rather than later could reduce your long-term cost. On the other hand, if you expect your income documentation to improve significantly in the next year, it might be worth waiting for both better rates and a stronger application.
There's no universally correct answer here, and the right timing will depend on your individual circumstances. Consulting with a knowledgeable loan officer who understands both the rate environment and the nuances of variable income qualification can help you make a well-informed decision.
Common Pitfalls to Avoid When You Refinance ARM Variable 1099 Overtime Income
Borrowers who refinance ARM variable 1099 overtime income situations sometimes run into avoidable problems. Being aware of these pitfalls ahead of time can save you time, money, and frustration.
Assuming Your Income Looks the Same to Lenders as It Does to You
It's easy to think of your income as the total amount deposited into your bank account. But lenders — especially for 1099 earners — often look at your taxable income after deductions. If your tax strategy involves maximizing write-offs, your qualifying income could be substantially lower than your gross receipts. Understanding this gap early is essential.
Shopping with Only One Lender
Different lenders have different overlays and interpretations of guidelines. One lender might disqualify your overtime income entirely, while another may count it fully with the right documentation. Shopping around — ideally with a mortgage broker who works with multiple wholesale lenders — gives you a broader view of what's actually available to you.
Neglecting the Break-Even Analysis
Refinancing comes with closing costs, which typically range from a few thousand dollars to more. If you're planning to sell the home or pay off the mortgage in the near future, the savings from a lower rate might not offset those upfront costs. Running a break-even analysis — dividing your closing costs by your monthly savings — can help you determine whether refinancing makes financial sense at this time.
●Conclusion
Navigating the best options for refinancing ARM mortgage with variable 1099 overtime pay requires a clear understanding of how lenders view your income, which loan programs may be the best fit, and how to position your application for success. While the process is more nuanced for variable income earners than for traditional W-2 borrowers, it's far from impossible. Many homeowners in exactly this situation successfully refinance each year by choosing the right program, preparing thorough documentation, and working with lenders experienced in non-traditional income scenarios. At LoanWise, we're here to help you explore your options with confidence. Reach out to one of our mortgage specialists today to get a personalized assessment of your refinance possibilities.